
Zero-risk profit! Invest ₹5 lakh in POTD and get this much return in 3 years.
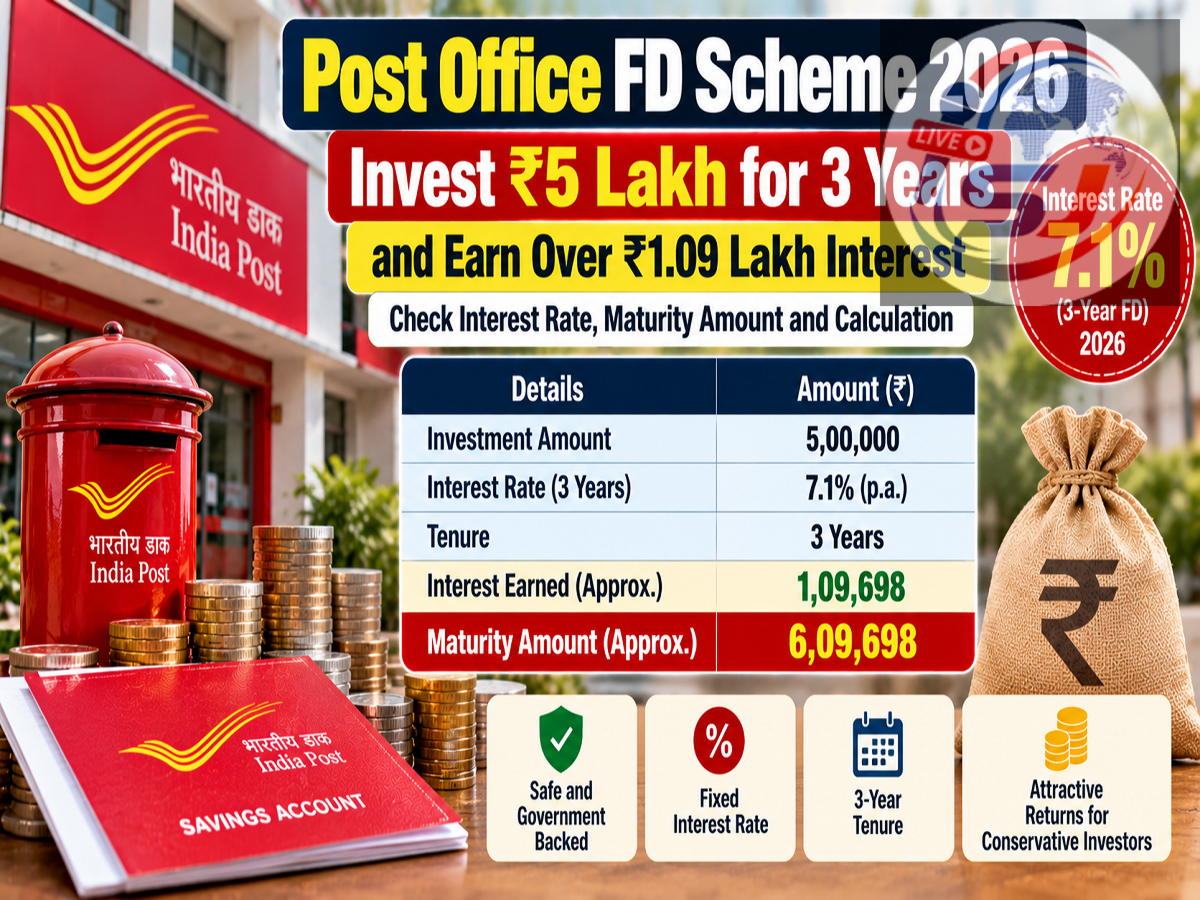
Post Office Time Deposit Scheme 2026: Investors who want to protect their savings from stock market volatility while earning predictable interest can consider the Post Office Time Deposit (POTD) scheme. This government-backed savings product offers fixed interest rates and multiple investment tenures, making it suitable for individuals seeking stable returns.
As of October 22, 2026, the three-year Post Office Time Deposit offers an annual interest rate of 7.1%. At this rate, an investment of ₹5 lakh can generate approximately ₹1.09 lakh in interest over three years, before tax.
The scheme is available for 1, 2, 3 and 5 years, with different interest rates for each period.
The government has retained the existing small savings interest rates for the October–December 2026 quarter, providing clarity for individuals planning new deposits.
Post Office Time Deposit Interest Rates: October–December 2026
The Ministry of Finance reviews interest rates on small savings schemes every quarter.
For the quarter beginning October 1 and ending December 31, 2026, the government has kept Post Office Time Deposit interest rates unchanged.
The applicable rates are:
| Investment Tenure | Annual Interest Rate |
|---|---|
| 1-Year Time Deposit | 6.9% |
| 2-Year Time Deposit | 7.0% |
| 3-Year Time Deposit | 7.1% |
| 5-Year Time Deposit | 7.5% |
The five-year option currently offers the highest rate among the available Time Deposit tenures.
These rates apply to eligible accounts opened during the notified quarter.
₹5 Lakh Investment for 3 Years: How Much Interest Will You Earn?
Suppose an investor opens a three-year Post Office Time Deposit account with ₹5,00,000.
At the applicable annual rate of 7.1%, the approximate annual interest is calculated using quarterly compounding within each interest year.
The calculation is:
Annual Interest = ₹5,00,000 × [(1 + 0.071/4)⁴ − 1]
This produces approximately ₹36,456 in interest annually.
Over three years, the total interest is approximately ₹1,09,368.
Post Office FD ₹5 Lakh Return Calculation
| Particulars | Amount |
|---|---|
| Initial Investment | ₹5,00,000 |
| Deposit Tenure | 3 Years |
| Interest Rate | 7.1% Per Annum |
| Approximate Annual Interest | ₹36,456 |
| Total Interest Over 3 Years | ₹1,09,368 |
| Principal Amount | ₹5,00,000 |
| Principal Plus Total Interest | ₹6,09,368 |
Important: Post Office Time Deposit interest is payable annually, not automatically accumulated until maturity.
Therefore, ₹6,09,368 represents the total principal and interest received over the three-year period, rather than a guaranteed single maturity payment.
The actual amounts are subject to prescribed rounding and scheme rules.
How Much Will ₹5 Lakh Earn in 1, 2, 3 and 5 Years?
Investors can compare the approximate interest income across all four available tenures.
| Deposit Period | Interest Rate | Approximate Total Interest |
|---|---|---|
| 1 Year | 6.9% | ₹35,656 |
| 2 Years | 7.0% | ₹71,859 |
| 3 Years | 7.1% | ₹1,09,368 |
| 5 Years | 7.5% | ₹1,92,856 |
These estimates assume that the interest payable each year is received separately and is not reinvested.
Longer deposits generate more total interest because the money remains invested for a greater number of years.
However, investors should choose their tenure based on when they expect to need the funds.
How Does the Post Office Time Deposit Scheme Work?
The Post Office Time Deposit scheme allows eligible investors to deposit a lump sum for a predetermined period.
The interest rate applicable when the account is opened determines the interest payable during the selected tenure.
Unlike stock market investments, the return is not directly affected by daily changes in equity prices.
Interest is calculated quarterly and paid annually.
If an investor does not withdraw the annual interest after it becomes payable, the unpaid amount does not automatically earn additional Time Deposit interest.
This distinction is important because some online calculators assume that interest compounds continuously throughout the entire deposit period.
Such calculations can overstate the amount available at maturity under the actual scheme.
What Is the Minimum Investment Amount?
The minimum investment required to open a Post Office Time Deposit account is ₹1,000.
Additional investment amounts must generally be in multiples of ₹100.
There is no prescribed maximum deposit limit under the standard scheme rules.
This means an eligible investor can deposit ₹5 lakh or another permitted amount, subject to the applicable account-opening and compliance requirements.
The scheme also permits multiple accounts, making it possible to distribute savings across different maturity periods.
Who Can Open a Post Office Time Deposit Account?
The scheme is available to eligible individuals under India Post's savings account rules.
A single adult can open an account in their own name.
Joint accounts are also permitted for up to three adults.
A guardian may open an account on behalf of a minor, while a minor aged 10 years or older may be eligible to open an account independently under the applicable conditions.
Investors should verify identity requirements, nomination details and account-opening procedures before depositing funds.
Is Post Office FD Completely Risk-Free?
Post Office Time Deposits are backed by the Government of India, providing a high degree of security for the principal and the interest payable under the scheme.
They are not linked to stock market performance.
However, the phrase “zero risk” should be interpreted carefully.
Inflation can reduce the purchasing power of the money received in future years.
There is also a liquidity consideration because withdrawing the deposit before maturity may result in reduced interest.
Additionally, the interest earned is generally taxable according to the investor's applicable income-tax provisions.
Therefore, the scheme offers government-backed, predictable nominal returns rather than protection from every financial risk.
Can You Withdraw a Post Office FD Before Maturity?
Premature withdrawal is permitted under specified conditions.
Generally, a Time Deposit cannot be closed before six months from the date of opening.
If it is closed after six months but before completing one year, interest is calculated using the applicable Post Office Savings Account rate instead of the contracted Time Deposit rate.
Different rules apply to deposits closed after one year, depending on the original tenure and elapsed period.
These provisions can substantially reduce the effective return.
Investors should avoid placing their entire emergency savings in a fixed-term account if they may require immediate access to the money.
Does the Post Office Time Deposit Offer Tax Benefits?
The tax treatment depends on the selected tenure and applicable income-tax rules.
Interest earned on Post Office Time Deposits is generally taxable.
The five-year Time Deposit qualifies as a tax-saving investment under the applicable deduction provisions, subject to the taxpayer's tax regime and eligibility.
However, the one-year, two-year and three-year Time Deposit options do not provide the same five-year deposit deduction.
Investors should also remember that eligibility for a deduction on the principal investment does not automatically make the interest income tax-free.
Post Office FD vs Bank FD: What Should Investors Compare?
Both Post Office Time Deposits and bank fixed deposits are popular among individuals seeking predictable returns.
However, their terms may differ.
Bank fixed deposits may offer flexible maturity periods, special interest rates for eligible senior citizens, and different interest payout options.
Post Office Time Deposits provide government-backed returns at the notified rates.
Investors should compare the interest rate, taxation, premature withdrawal conditions, payout frequency and account convenience.
The effective after-tax return is particularly important for individuals in higher income-tax brackets.
How to Open a Post Office Time Deposit Account
Interested investors can visit an authorised post office offering savings banking services.
They should select the preferred tenure, complete the required account-opening documentation and provide the necessary KYC details.
The deposit can then be made through the permitted payment method.
Eligible existing customers may also have access to supported online services.
Before opening the account, investors should confirm the current interest rate, annual payout arrangements, nomination facility and premature closure conditions.
Official details are available through the India Post website at https://www.indiapost.gov.in/.
Final Word
The Post Office Time Deposit scheme offers a government-backed savings option for individuals seeking predictable returns without direct stock market exposure.
At the current 7.1% annual interest rate, a ₹5 lakh deposit for three years can generate approximately ₹1,09,368 in total interest before tax.
The combined principal and interest over the period would be approximately ₹6.09 lakh, with interest paid annually and the principal returned at maturity.
Investors seeking a longer-term option can also consider the five-year Time Deposit, which currently offers 7.5% annual interest.
Before investing, it is important to review liquidity needs, tax implications and the applicable scheme conditions.
Disclaimer: Interest calculations are approximate and intended for illustration. Rates cited are applicable to new accounts opened during October–December 2026. Actual payments are governed by India Post rules and prescribed rounding procedures.
Correct the three-year interest calculationClarify annual payouts versus maturity value