
Post Office RD: Save ₹300 a Day to Build Over ₹6 Lakh in 5 Years, Check the Calculation
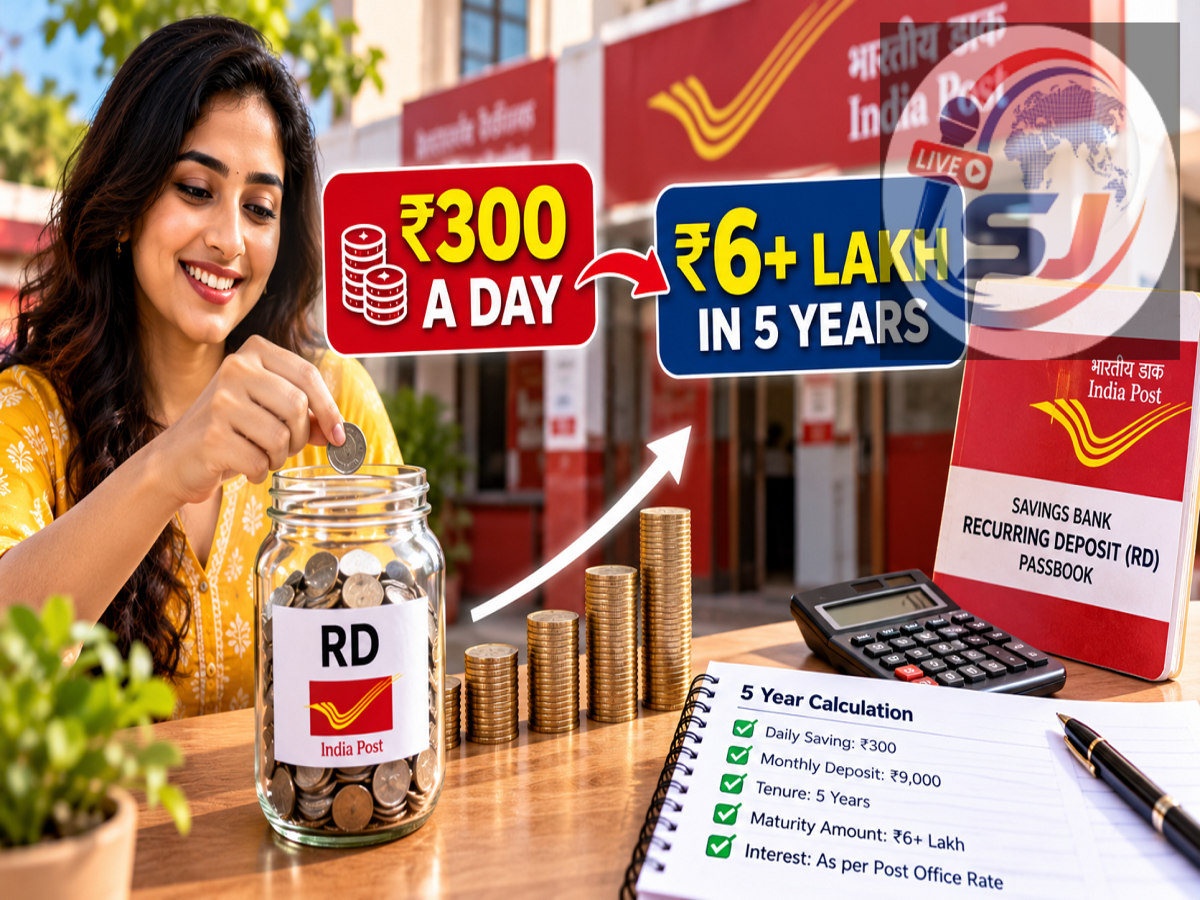
Building a sizeable savings corpus does not always require a large one-time investment. A disciplined approach to putting aside a small amount regularly can also help create a substantial fund over several years. The Post Office Recurring Deposit (RD) scheme is one such option for people who prefer regular savings and government-backed small savings products.
For example, if you manage to save ₹300 every day, that works out to roughly ₹9,000 a month when calculated on the basis of 30 days. Instead of leaving this money unused, you could use ₹9,000 as your monthly contribution to a five-year Post Office RD.
At an annual interest rate of 6.7%, regular deposits of this size can potentially create a corpus of more than ₹6 lakh over five years.
It is important, however, to understand that Post Office RD contributions are made as monthly instalments. You do not deposit ₹300 into the RD every day. The daily amount is simply a way of planning the ₹9,000 monthly saving target.
How Does the Post Office RD Scheme Work?
A Recurring Deposit is designed for people who want to invest a fixed amount every month instead of making a large lump-sum deposit.
The Post Office RD has a standard maturity period of five years, or 60 monthly instalments. Interest is calculated according to the rate applicable under the scheme and is compounded quarterly.
At the stated annual interest rate of 6.7%, consistent monthly investments can generate additional returns over the five-year tenure.
Since the scheme encourages regular contributions, it may suit salaried employees, small business owners and other individuals looking to develop a disciplined saving habit.
₹300 Daily Saving Means Around ₹9,000 Per Month
Suppose your target is to save ₹300 every day.
Using a simple 30-day monthly estimate:
₹300 × 30 = ₹9,000
This gives you approximately ₹9,000 to invest each month.
If this amount is deposited into a Post Office RD every month for five years, you will make 60 monthly deposits.
Your total contribution would therefore be:
₹9,000 × 60 = ₹5,40,000
So, even before adding interest, you would have personally contributed ₹5.40 lakh during the five-year period.
How Much Can ₹9,000 Monthly Become in 5 Years?
According to the calculation provided for the scheme, an investment of ₹9,000 every month at an annual interest rate of 6.7% can grow to approximately ₹6.42 lakh over five years.
The indicative calculation is:
Monthly RD deposit: ₹9,000
Investment period: 5 years or 60 months
Total amount deposited: ₹5,40,000
Annual interest rate: 6.7%
Estimated interest earned: Around ₹1,02,292
Estimated maturity amount: Around ₹6,42,292
This means an investor contributes ₹5.40 lakh from their own pocket, while interest could add roughly another ₹1.02 lakh by maturity, taking the total to approximately ₹6.42 lakh.
The final amount can vary according to the applicable Post Office RD rules, deposit timing, interest calculation and the rate available for the account.
Can You Actually Deposit ₹300 Every Day in an RD?
The phrase "save ₹300 daily" can sometimes create confusion.
A Post Office RD is based on monthly deposits rather than a requirement to make a ₹300 payment every single day.
The ₹300 figure is better understood as a personal savings target. Someone could put aside ₹300 each day and then use the accumulated amount to make the monthly RD instalment of approximately ₹9,000.
This approach can make a relatively large monthly savings target feel more manageable.
What Is the Minimum Investment in Post Office RD?
The Post Office RD can be started with a relatively small monthly contribution.
According to the scheme details cited in the source information, the minimum monthly deposit is ₹100. Deposits above this amount can be made in prescribed multiples, and there is no stated maximum investment ceiling for the account.
This flexibility means investors do not necessarily need to invest ₹9,000 every month. They can choose an amount according to their income, expenses and savings capacity.
The key is to select a monthly instalment that can be maintained consistently.
Why Compounding Matters
One of the important features of an RD is that investors do not earn returns only on their deposits. Over time, compounding helps the accumulated interest contribute to further growth.
In the Post Office RD, interest is compounded quarterly according to the applicable scheme rules.
The effect of compounding becomes more noticeable as the investment period increases. This is one reason regular long-term saving can build a much larger corpus than simply looking at the monthly instalment amount.
Is Post Office RD a Safe Investment?
Post Office RD is part of the government's small savings framework. Unlike market-linked investments, its returns are not directly dependent on daily stock-market movements.
That can make it attractive to conservative savers who prioritise predictable returns and capital safety over potentially higher but market-dependent returns.
However, investors should still compare the RD with other savings and investment options based on their financial goals, liquidity needs, tax position and expected returns.
Does the 6.7% Interest Rate Remain the Same Forever?
Investors should not assume that the interest rate mentioned for a small savings scheme will remain unchanged indefinitely for all future investments.
The government reviews interest rates on small savings schemes periodically, generally on a quarterly basis. Therefore, anyone planning to open a new Post Office RD should check the interest rate officially applicable at the time of opening the account.
The maturity amount shown in an illustration is also an estimate based on the assumptions used in the calculation.
Regular Saving Can Make a Big Difference
The biggest lesson from the ₹300-a-day example is the power of disciplined saving.
Putting aside ₹300 may appear relatively small on a daily basis, but it translates into around ₹9,000 over a 30-day month. Maintaining that monthly saving for five years results in ₹5.40 lakh in personal contributions alone.
With interest added, the illustrated corpus could reach approximately ₹6.42 lakh.
For people who want a structured savings option without direct exposure to market fluctuations, the Post Office RD can be worth considering. Before investing, however, check the latest interest rate, deposit rules, premature withdrawal provisions, extension options and other terms through official Post Office or government sources.