Post Office RD 2026: Start Saving With Just ₹100 a Month, Check Interest, Loan and Account Rules
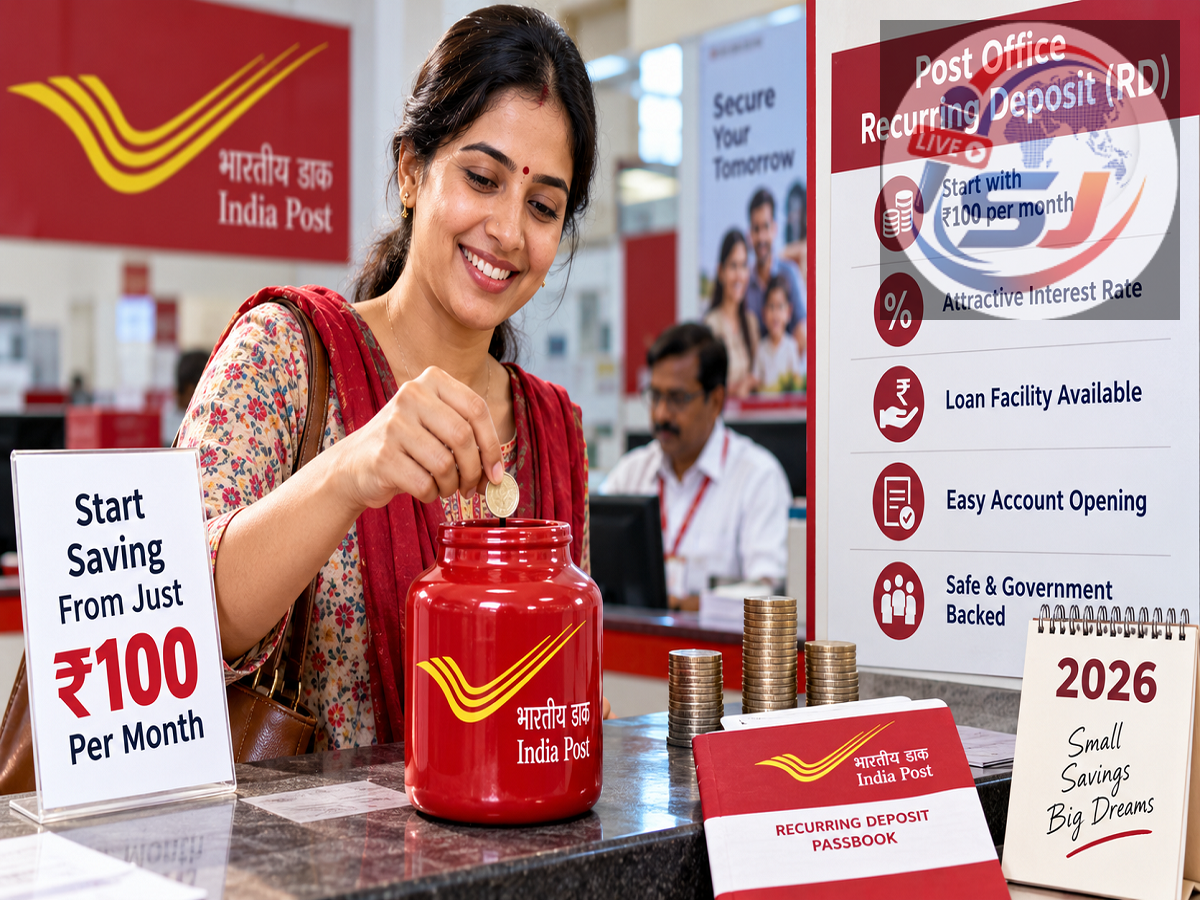
Building a sizeable savings corpus does not always require a large investment at the beginning. For people who prefer putting aside a fixed amount every month, the Post Office Recurring Deposit (RD) scheme provides a simple way to develop a disciplined savings habit while earning returns that are not linked to stock-market movements.
The scheme is particularly accessible because an RD account can be started with a monthly deposit of just ₹100. Investors can choose a higher contribution according to their financial capacity, making the product suitable for people with different income and savings levels.
The Post Office RD has a standard maturity period of five years, or 60 monthly deposits. It also offers features such as a loan facility after fulfilling prescribed conditions and premature closure after the minimum period allowed under the rules.
Here is a detailed look at how the Post Office RD works, who can open an account and what investors should check before starting one in 2026.
Start a Post Office RD With ₹100 Per Month
One of the biggest advantages of the scheme is its low entry requirement.
The minimum monthly deposit is ₹100, and higher deposits can be made in multiples prescribed under the applicable Post Office Savings Scheme rules. There is no need to begin with thousands of rupees every month simply to open the account.
For example, someone saving ₹500, ₹1,000, ₹2,000 or ₹5,000 every month can choose a contribution according to their budget.
Regular monthly deposits can gradually build a meaningful corpus over the five-year tenure, while interest further adds to the maturity amount.
How Long Does a Post Office RD Run?
A Post Office Recurring Deposit account normally matures after five years from the date it is opened.
This means investors commit to making regular monthly deposits throughout the tenure.
The five-year period makes RD different from a normal savings account. Instead of depositing and withdrawing money frequently, the investor follows a structured savings schedule designed to build a corpus over time.
The account may also be continued beyond its original maturity under the extension provisions applicable to the scheme.
What Is the Post Office RD Interest Rate?
The interest rate on Post Office small-savings schemes is notified by the government and is reviewed periodically.
Investors should therefore check the latest officially applicable Post Office RD interest rate when opening an account instead of relying on an old rate found online.
Interest in an RD accumulates according to the scheme's prescribed compounding method, helping monthly contributions grow over the investment period.
Unlike equity or mutual-fund investments, returns on a Post Office RD are not determined by daily movements in the stock market.
This can make it appealing to conservative savers who prioritise predictability over market-linked growth potential.
How Much Can You Build in Five Years?
The maturity corpus depends primarily on two factors: the amount deposited every month and the applicable interest rate.
Consider someone investing ₹1,000 every month. Over 60 months, the investor would contribute a total principal of:
₹1,000 × 60 = ₹60,000
The final maturity amount would be higher than the ₹60,000 deposited because interest would also accumulate according to the applicable RD rate and calculation rules.
Similarly, a monthly contribution of ₹5,000 would result in total deposits of ₹3 lakh over five years, before adding the interest earned.
The exact maturity value should be calculated using the interest rate applicable to the account rather than assuming a fixed return for every new investment.
Loan Facility Available Against Post Office RD
An important feature of the Post Office RD is that an eligible account holder may be able to borrow against the account instead of immediately closing it during a financial emergency.
Under the applicable conditions, once the account has remained active for the required period and the necessary number of instalments has been deposited, the account holder can apply for a loan of up to the prescribed portion of the balance.
The reported scheme provisions allow a loan of up to 50% of the eligible balance after 12 instalments and one year of continuation, subject to the prevailing rules.
Interest applies to the loan, so borrowers should understand its cost and repayment conditions before using the facility.
Can You Close an RD Before Five Years?
Post Office RD is designed as a five-year savings product, but premature closure is permitted under specified conditions.
According to the applicable scheme framework, premature closure can generally be requested after three years from the date of opening, subject to the relevant rules.
The return payable on premature closure may not be the same as the amount an investor would have earned by keeping the RD until maturity.
Therefore, investors should avoid putting all their emergency savings into an RD. Maintaining some easily accessible money separately can reduce the likelihood of having to close the account early.
What Happens If You Miss a Monthly Instalment?
Because RD is based on regular savings, monthly deposits need to be made according to the prescribed schedule.
Missing an instalment can lead to a default, and the account holder may need to pay the applicable default fee while regularising the account.
Repeated defaults can also affect the account's operation under the scheme rules.
Investors should therefore select a monthly contribution they can comfortably maintain for the entire five-year period rather than committing to an unnecessarily high amount.
Who Can Open a Post Office RD Account?
Eligible adults can open an RD account individually, and joint-account facilities are also available according to the applicable Post Office Savings Scheme rules.
Accounts can also be opened for minors under prescribed conditions. A guardian can operate an account on behalf of a minor, while eligible minors above the specified age may be permitted to operate an account in their own name according to the rules.
This can make an RD useful for families saving gradually towards future expenses.
How to Open a Post Office RD Account
Those interested in opening an account can visit an eligible post office and complete the prescribed application process.
Applicants should carry the KYC and other documents required by the Post Office. These may include Aadhaar, PAN and other accepted identity or address documentation depending on the customer's circumstances and prevailing requirements.
Complete the application, provide the required KYC information and make the initial deposit.
Once the account is opened, keep the account details and deposit records safely.
Digital facilities may also make it easier for eligible customers to manage or fund Post Office savings products, depending on the accounts and services they have activated.
Is Post Office RD Right for You?
Post Office RD can be worth considering for people who want to save a fixed amount every month without taking market-linked investment risk.
The ability to begin with ₹100 per month, a structured five-year tenure and access to a loan facility under specified conditions make it suitable for disciplined small savings.
However, an RD should not automatically be considered the best option for every financial goal. Investors should compare its interest rate, taxation, liquidity and expected returns with alternatives such as bank RDs, fixed deposits and other government-backed savings products.
For anyone considering a Post Office RD in 2026, the most important step is to check the latest official interest rate and scheme conditions before opening the account. Choosing a manageable monthly contribution and continuing it consistently can turn even relatively small savings into a useful corpus over five years.