
Post Office NSC: How a One-Time Investment Can Earn Around ₹4.5 Lakh in Interest
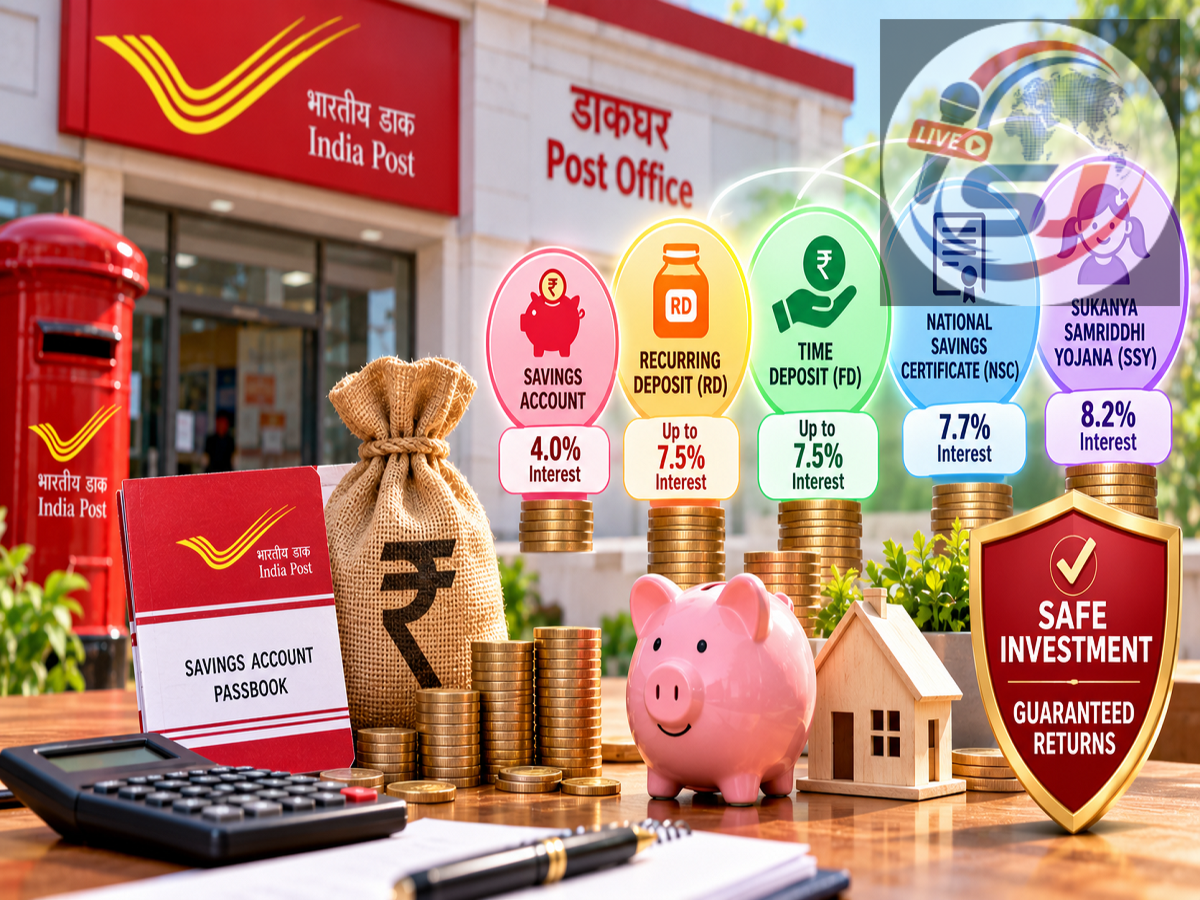
Investors looking for a government-backed savings option with predictable returns often consider Post Office small savings schemes. Among these, the National Savings Certificate (NSC) is a popular choice for people who want to invest a lump sum for five years while also getting eligible income-tax benefits.
The NSC currently offers an interest rate of 7.7% per annum, compounded annually and payable at maturity. Since the scheme is backed by the Government of India, it does not carry the same market-price risk as equity or market-linked mutual fund investments.
One illustration shows how a sufficiently large one-time investment in NSC can generate roughly ₹4.5 lakh from interest alone over its five-year tenure.
However, investors should understand the deposit requirement, maturity calculation, taxation and withdrawal rules before investing.
What Is the Post Office National Savings Certificate?
National Savings Certificate is a government small savings scheme available through Post Offices.
Unlike a recurring deposit, investors do not have to contribute money every month. An eligible investor can make a lump-sum investment and allow it to accumulate interest over the five-year maturity period.
The scheme is particularly relevant to investors who want predictable returns and do not want their investment value to fluctuate with daily movements in the stock market.
NSC currently offers an annual interest rate of 7.7%.
The government reviews small-savings interest rates periodically, so the rate applicable to a new investment should always be checked before opening the account.
How Can You Earn Around ₹4.5 Lakh From Interest?
The attraction of NSC becomes easier to understand with an example.
Suppose an investor puts approximately ₹10 lakh into NSC for its five-year maturity period.
At an annual compounded rate of 7.7%, ₹10 lakh can grow to roughly ₹14.49 lakh after five years.
This means the approximate calculation would be:
Initial investment: ₹10,00,000
Approximate maturity value: ₹14.49 lakh
Approximate interest earned: ₹4.49 lakh
In other words, the investor could earn close to ₹4.5 lakh in interest over five years if the investment is made at the applicable 7.7% rate and held until maturity.
The figure should be treated as an illustration based on the scheme's applicable interest calculation rather than a promise that future NSC issues will always carry the same interest rate.
What If You Invest ₹5 Lakh?
Investors do not necessarily need ₹10 lakh to use NSC.
For example, a ₹5 lakh investment at the same 7.7% annual compounded rate would grow substantially over five years.
Since the return is linked to the amount invested, a smaller principal will generate proportionately lower interest than the ₹10 lakh example.
Similarly, investors who put in a higher amount would accumulate more interest, subject to applicable scheme and tax rules.
Minimum Investment Starts at ₹1,000
One of the advantages of NSC is that investors do not need several lakh rupees to open an account.
The minimum investment is ₹1,000, after which deposits can be made in prescribed multiples.
There is generally no specified upper investment ceiling under the NSC scheme.
However, this should not be confused with the income-tax deduction limit.
An investor may be permitted to invest more than ₹1.5 lakh in NSC, but the deduction available under Section 80C is subject to the overall statutory limit and applicable tax regime and conditions.
NSC Comes With a Five-Year Lock-In
National Savings Certificate has a maturity period of five years.
This makes NSC different from a normal savings account where funds can generally be withdrawn whenever needed.
Premature closure of an NSC account is allowed only under specified circumstances under the scheme rules.
Investors should therefore avoid putting emergency money into NSC if they may need unrestricted access to those funds before the five-year maturity date.
For money that may be required at short notice, maintaining a separate liquid emergency fund can be more appropriate.
NSC Can Offer Section 80C Tax Benefits
NSC has traditionally been popular not only because of its government backing but also because eligible investments can qualify for deduction under Section 80C of the Income Tax Act, subject to applicable conditions.
The overall Section 80C deduction limit is ₹1.5 lakh in a financial year under the applicable tax framework.
This does not mean an investor cannot put more than ₹1.5 lakh into NSC. It means the tax deduction cannot simply be increased beyond the statutory overall Section 80C limit by making a larger NSC investment.
Tax benefits also depend on the tax regime selected by the taxpayer and the income-tax rules applicable for the relevant financial year.
Is NSC Interest Completely Tax-Free?
No. Investors should not confuse a Section 80C-eligible investment with a completely tax-free investment.
Interest earned on NSC is generally taxable according to applicable income-tax provisions.
Because the interest is compounded and reinvested during much of the tenure, its tax treatment can involve specific rules. Investors should check the current provisions or consult a tax professional when filing their return.
This distinction is particularly important for people investing large amounts primarily because of the advertised maturity value.
Is NSC Really a 'Zero-Risk' Investment?
NSC is backed by the Government of India and does not expose investors to stock-market fluctuations in the way equity investments do.
Its applicable interest rate and maturity framework provide considerably more predictability than market-linked products.
However, describing any financial product simply as having “zero risk” can be misleading.
Investors still need to consider factors such as inflation risk, liquidity restrictions and taxation.
For example, if inflation remains high, the purchasing power of the final maturity amount may not grow as much as the nominal return suggests.
Therefore, NSC is better described as a government-backed savings product with predictable returns, rather than as an investment carrying no conceivable financial risk.
NSC vs Market-Linked Investments
NSC serves a very different purpose from equity mutual funds or direct stock-market investments.
The value of an equity investment can rise or fall significantly depending on market conditions. NSC, by comparison, is designed to provide returns according to the interest rate applicable to the investment under government small-savings rules.
The trade-off is that investors do not get unlimited upside if equity markets rally sharply.
NSC may therefore appeal more to conservative investors whose priority is predictability and capital stability rather than aggressive wealth creation.
Who May Consider National Savings Certificate?
NSC may be worth evaluating for investors who have a five-year financial horizon and prefer a government-backed savings instrument.
It can also be useful for eligible taxpayers seeking a Section 80C investment option under the applicable tax regime.
However, investors should first ensure they have enough liquid savings for emergencies because NSC is not designed for unrestricted withdrawals during its five-year tenure.
At the current cited interest rate of 7.7%, an investment of around ₹10 lakh can grow to approximately ₹14.49 lakh over five years, generating close to ₹4.5 lakh in interest.
For conservative savers, that combination of government backing, predictable interest and a defined maturity period is what makes the National Savings Certificate one of the notable Post Office savings options.
Disclaimer: This article is for general information only and should not be treated as financial or tax advice. Small-savings interest rates are reviewed periodically by the government. Tax benefits depend on the applicable tax regime and prevailing laws. Investors should verify the latest NSC rules and interest rate before investing.