PMJJBY 2026: Get ₹2 Lakh Life Cover for ₹436 a Year, Check Eligibility and Auto-Debit Rules
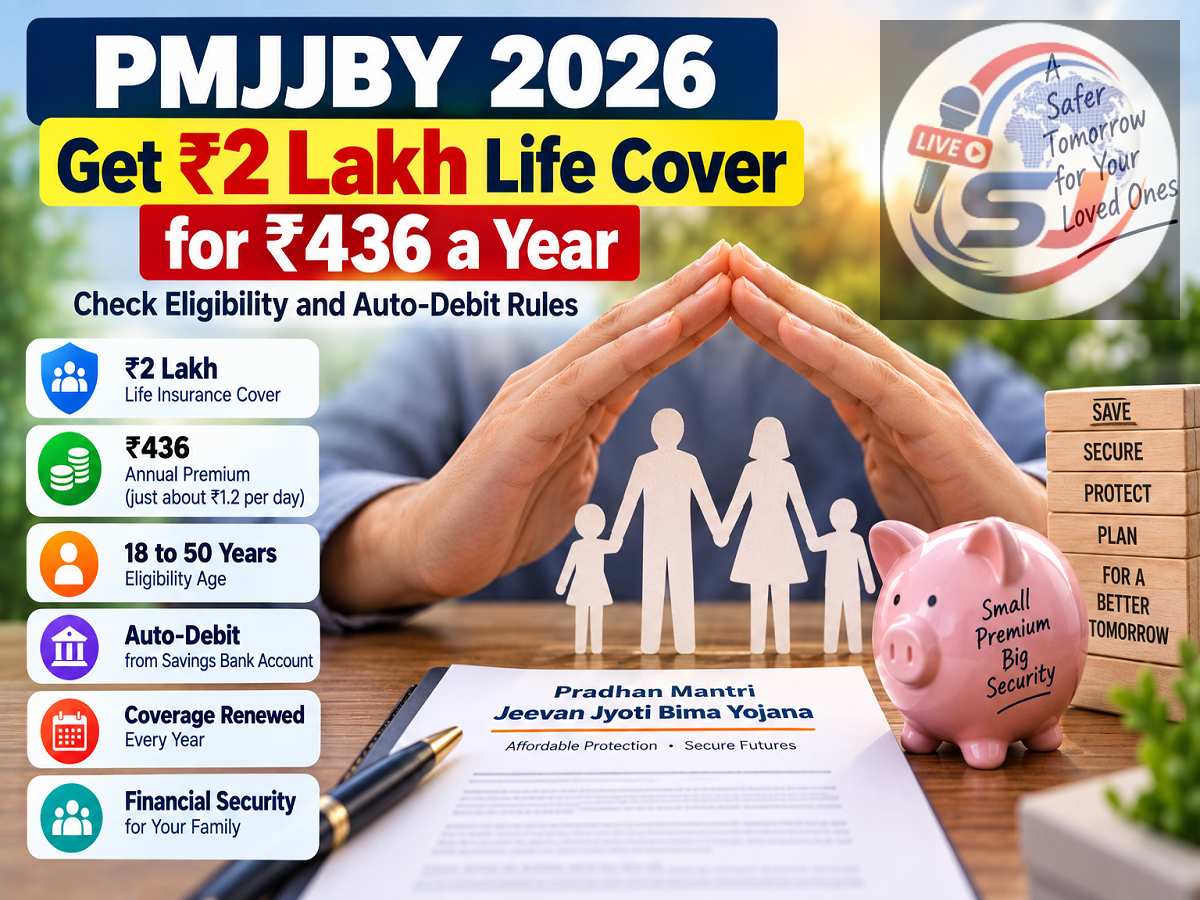
The Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY) is a government-backed life insurance scheme designed to provide affordable financial protection to eligible individuals and their families. With an annual premium of ₹436, the scheme provides ₹2 lakh life insurance coverage in the event of the insured person's death, subject to the applicable terms and conditions.
The scheme is particularly aimed at making basic life insurance accessible at a relatively low cost. Instead of requiring policyholders to manually pay the premium every year, PMJJBY uses an auto-debit mechanism, under which the applicable premium is deducted from the enrolled bank or post-office savings account after the account holder has provided consent.
The standard coverage cycle runs from June 1 to May 31 of the following year.
People considering PMJJBY should understand the age criteria, auto-debit requirements, nomination process and claim conditions before enrolling.
How Much Does PMJJBY Cost?
The standard annual premium under PMJJBY is ₹436 per member for a full-year coverage cycle.
At this premium, the insured person receives life insurance cover of ₹2 lakh, subject to the scheme rules.
| PMJJBY Feature | Details |
|---|---|
| Annual premium | ₹436 |
| Life insurance cover | ₹2 lakh |
| Entry age | 18 to 50 years |
| Annual coverage period | June 1 to May 31 |
| Premium payment | Auto-debit from enrolled account |
| Type of benefit | Life insurance on death, subject to scheme conditions |
The ₹436 premium applies to the full annual cycle. Different premium amounts may apply when a person joins after the beginning of the policy year under the applicable pro-rata structure.
Who Can Join PMJJBY?
People between 18 and 50 years of age who hold an eligible savings bank account or post-office savings account can enrol in PMJJBY, subject to the prescribed rules.
Enrollment requires the account holder to provide consent for the premium to be automatically debited.
The scheme does not operate like a conventional individual life insurance policy requiring an elaborate underwriting process. Enrollment is designed to be relatively simple, although applicants must provide the declarations and information required under the scheme.
Those joining after the specified period should carefully review any applicable conditions, including rules governing when risk coverage begins.
How Does the Auto-Debit System Work?
One of PMJJBY's key features is automatic premium collection.
Once an eligible account holder enrols and gives the required auto-debit authorisation, the applicable premium can be deducted directly from the designated savings account.
For the standard annual renewal cycle, the account should have enough money available when the premium is due.
This means policyholders do not normally need to visit a branch each year solely to make a manual premium payment.
However, maintaining sufficient balance is important.
If the premium cannot be debited because the account does not have adequate funds or because of another account-related issue, continuation of insurance coverage can be affected.
Account holders should therefore check their bank statement or policy status instead of assuming that renewal has automatically been completed.
What Happens If You Join During the Year?
A person does not necessarily have to enrol only at the beginning of June.
PMJJBY provides for enrollment during the policy year, subject to the applicable conditions.
In such situations, the premium may be charged on a pro-rata basis depending on the quarter in which enrollment takes place, rather than charging the full ₹436 in every case.
The applicable amount and coverage conditions should be checked with the participating bank, post office or insurer at the time of enrollment.
This is particularly important because the premium payable for late enrollment and the effective date of risk coverage can depend on the scheme's current rules.
How Can You Apply for PMJJBY?
PMJJBY is available through participating banks and post offices in association with life insurance companies.
Many banks provide digital enrollment facilities through internet banking or mobile banking. The exact menu names and process can vary between institutions.
Where the facility is available, a customer generally needs to sign in to the bank's official app or internet-banking service and locate the section for government or social-security insurance schemes.
After selecting PMJJBY, the customer may be asked to choose the relevant savings account, provide or confirm nominee details and authorise auto-debit of the applicable premium.
Customers should follow the instructions displayed by their own bank because the enrollment process is not necessarily identical across all institutions.
Those who cannot find the option online can contact their bank or post-office branch for assistance.
Nominee Details Are Important
Policyholders should provide accurate nominee information when enrolling.
The nominee is important because the insurance benefit is intended to provide financial support after the insured person's death.
Incorrect or outdated information can create complications during the claim process.
Customers should therefore review the nominee's name and other required details carefully and update them through the appropriate channel if circumstances change.
What Does the Family Receive After the Insured Person's Death?
PMJJBY provides ₹2 lakh life insurance cover on death due to any cause, subject to the terms and conditions of the scheme.
When the insured person dies, the nominee or eligible claimant needs to initiate the claim process through the relevant bank, post office or insurer.
Documents generally required for processing may include the prescribed claim form, death certificate and relevant claimant or nominee information.
The documents are then checked according to the applicable procedure. Once a valid claim is approved, the insurance benefit is paid according to the scheme's claim-settlement process.
Customers should obtain the latest claim form and document checklist from their bank or insurer because requirements can vary depending on the circumstances.
Keep Enough Balance for Premium Deduction
Auto-debit makes PMJJBY renewal convenient, but it also places responsibility on the policyholder to keep the linked account operational and adequately funded.
Customers should periodically check whether the annual premium has actually been deducted.
A failed auto-debit should not be ignored, because it may affect continuation of coverage.
Similarly, changing or closing the linked savings account without updating the insurance arrangement could create problems with future premium collection.
Why PMJJBY Can Be Useful for Families
At ₹436 for a full-year premium, PMJJBY provides a basic level of life insurance protection at a relatively low cost.
For a family that depends financially on one earning member, a ₹2 lakh insurance payout could provide some immediate support after that person's death.
However, ₹2 lakh may not be sufficient to cover a family's long-term financial needs, outstanding loans, children's education and regular household expenses.
PMJJBY should therefore be understood as a basic social-security insurance cover rather than automatically being considered a complete replacement for a larger life insurance plan.
The most important points for existing members are to maintain sufficient balance in the linked account, verify successful premium deduction, keep nominee information updated and understand the applicable coverage conditions.
Disclaimer: Insurance coverage, enrollment, renewal and claim settlement are subject to the applicable PMJJBY rules and participating insurer/bank procedures. Customers should check the latest official terms with their bank, post office or insurer before enrollment.