
NPS After 60: You May Not Need to Withdraw Everything at Retirement—Know the Rules Up to Age 75
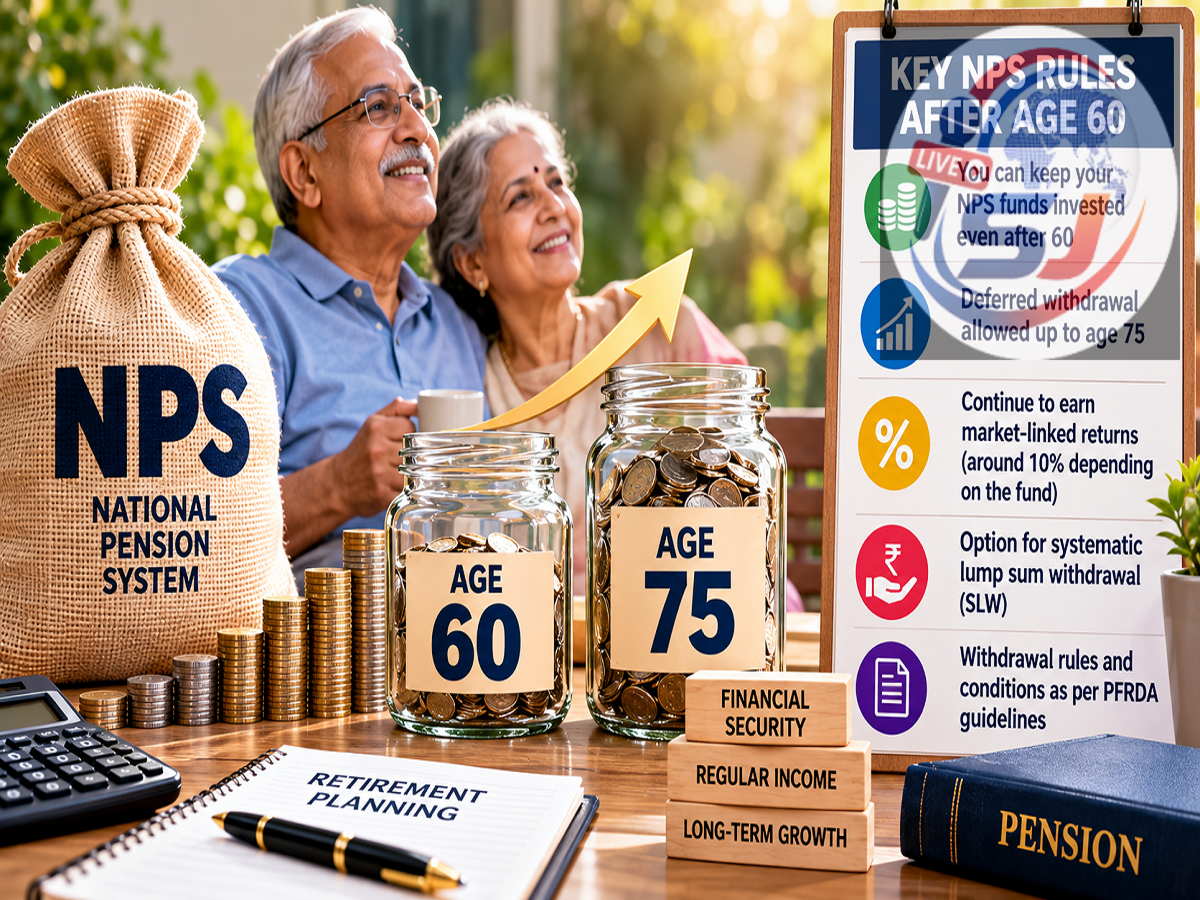
NPS Post-Retirement Rules: Turning 60 does not necessarily mean that a National Pension System (NPS) subscriber must immediately withdraw the entire eligible lump-sum amount and close the account. Depending on the applicable exit rules, subscribers can have options to defer certain withdrawals or receive the eligible lump-sum portion gradually.
These options can allow part of the retirement corpus to remain invested for longer, potentially giving it additional time to grow. However, there is an important distinction: NPS does not offer a fixed interest rate like a bank fixed deposit. Its returns are market-linked and can rise or fall depending on the underlying investments.
For retirees, understanding the withdrawal, annuity and deferment rules can therefore be just as important as building the NPS corpus itself.
What Happens to NPS When You Reach 60?
At normal exit from NPS, the accumulated retirement corpus is dealt with according to the applicable PFRDA exit and withdrawal rules.
Under the commonly applicable normal-exit framework, a subscriber may withdraw an eligible portion of the accumulated corpus as a lump sum, while the prescribed portion is used to purchase an annuity, subject to the rules and exemptions applicable to the subscriber.
The annuity is intended to generate pension income after retirement.
But subscribers do not necessarily have to rush to withdraw the entire eligible lump-sum component immediately upon reaching retirement age.
Depending on the applicable regulations, deferment and phased-withdrawal facilities can provide greater flexibility.
Option 1: Defer Your NPS Withdrawal
One important facility is deferment.
Instead of taking the eligible lump-sum amount immediately, subscribers may be able to defer withdrawal according to the applicable NPS rules.
The source information highlights the possibility of keeping eligible funds within the NPS framework up to age 75.
As long as the money remains invested, its value continues to depend on the performance of the NPS portfolio.
This can potentially provide additional growth, but it can also expose the corpus to market volatility.
Don't Call NPS Returns 'Guaranteed Interest'
This is particularly important for retirees comparing NPS with a fixed deposit.
An FD generally provides a predetermined interest rate for the chosen tenure, subject to the bank's terms.
NPS works differently.
NPS money is invested across permitted asset classes, which can include equities, corporate debt and government securities depending on the subscriber's allocation and applicable rules.
Therefore, figures such as 8%, 10% or 12% should be treated only as assumed or historical-return scenarios—not as promised future returns.
A retiree should not plan essential expenses on the assumption that NPS will definitely deliver 10% every year.
Option 2: Systematic Lump-Sum Withdrawal
Another facility that can provide flexibility is a phased or systematic withdrawal of the eligible lump-sum component.
Instead of withdrawing the entire eligible amount at once, a subscriber may be able to spread withdrawals over time according to the options permitted under PFRDA rules.
This can help retirees create a structured cash-flow plan.
The amount that remains invested can continue to participate in market performance until it is withdrawn.
Again, this means the remaining corpus can increase or decrease depending on investment returns.
Why Would Someone Delay the Lump-Sum Withdrawal?
Suppose a retiree does not need the entire lump-sum amount immediately.
Taking all the money out and placing it in a savings account may reduce its growth potential, particularly if the savings-account rate is relatively low.
Keeping an eligible amount invested through NPS can offer continued exposure to a diversified retirement portfolio.
At the same time, keeping money in NPS is not automatically the best option in every situation.
A retiree may need immediate liquidity for medical expenses, debt repayment, housing, emergency reserves or other financial commitments.
The appropriate decision therefore depends on cash-flow requirements, risk tolerance, tax position and retirement goals.
₹1 Crore NPS Corpus: How Continued Growth Could Work
Consider an illustrative example where a subscriber has accumulated an NPS corpus of ₹1 crore at age 60.
If a portion of the corpus remains invested, its future value will depend on actual market performance.
For illustration, here is how ₹60 lakh could potentially grow if it remained invested without withdrawals:
| Period | At 8% Assumed Return | At 10% Assumed Return | At 12% Assumed Return |
|---|---|---|---|
| Starting Amount | ₹60 lakh | ₹60 lakh | ₹60 lakh |
| After 5 Years | ~₹88.16 lakh | ~₹96.63 lakh | ~₹1.06 crore |
| After 10 Years | ~₹1.30 crore | ~₹1.56 crore | ~₹1.86 crore |
| After 15 Years | ~₹1.90 crore | ~₹2.51 crore | ~₹3.28 crore |
These numbers demonstrate the mathematical effect of compounding only.
They are not forecasts or guaranteed NPS maturity values. Actual returns can be higher or lower, and withdrawals, charges, asset allocation and market movements will affect the outcome.
Why Compounding Can Matter After Retirement
Retirement at 60 does not necessarily mean that every rupee in a retirement portfolio must stop growing.
For someone who lives to 80, 85 or 90, retirement itself can last 20 to 30 years.
That makes the period after retirement an important part of financial planning.
Money required for immediate expenses may need to be held in highly liquid and relatively stable instruments, while money that may not be needed for many years can potentially remain invested according to the retiree's risk capacity.
NPS withdrawal flexibility can form part of such a strategy, subject to the applicable regulations.
Is NPS Automatically Better Than a Bank FD?
No. Comparing NPS and an FD solely on an assumed return percentage can be misleading.
An FD offers a specified interest rate for its tenure, while NPS returns are linked to investment-market performance.
A bank FD can therefore provide greater predictability. NPS, on the other hand, can provide market-linked growth potential depending on asset allocation.
The two products also differ in liquidity, taxation, risk, withdrawal conditions and purpose.
For retirees, the appropriate choice depends on whether the money is meant for immediate expenses, emergency needs, regular income or long-term growth.
Tax Treatment Is Another Important Factor
Taxation can also influence retirement withdrawal decisions.
The eligible lump-sum withdrawal from NPS at normal exit receives tax treatment according to the provisions of the Income-tax Act and applicable NPS rules.
If tax-exempt money withdrawn from NPS is subsequently invested in an FD, the interest generated by that FD is generally taxable according to applicable income-tax provisions.
That is different from saying that the withdrawn principal becomes taxable simply because it is invested in an FD.
Retirees should consider both the tax treatment of the original withdrawal and the taxation of income subsequently generated from the withdrawn money.
Understand the Annuity Requirement
The annuity component is another major part of the NPS exit structure.
Under the normal exit framework commonly applicable to NPS subscribers, a prescribed portion of the corpus may need to be used to purchase an annuity, subject to the rules and exceptions applicable at the time of exit.
The source describes the standard framework as requiring at least 40% of the corpus for annuity purchase, with the remaining eligible portion available for lump-sum withdrawal.
However, subscribers should verify the current rules applicable to their NPS category and corpus when they actually exit, because regulations and thresholds can change.
What Does an NPS Annuity Do?
An annuity converts the applicable portion of the retirement corpus into pension income.
The amount of pension depends on several factors, including the amount used to purchase the annuity, the annuity provider, the selected plan and the annuity rate available at the time.
Different annuity options can also provide different benefits.
For example, a plan designed to continue income to a spouse may produce a different pension amount from a single-life annuity.
Subscribers should therefore compare annuity options instead of selecting solely on the basis of the initial monthly payout.
Should You Withdraw 60% Immediately?
The ability to withdraw an eligible portion does not mean every subscriber should automatically take the maximum amount on the first day of retirement.
Consider what the money will be used for.
If a large withdrawal simply remains unused in a low-interest savings account, the retiree may want to examine other permitted options.
On the other hand, if the money is needed for essential expenses, emergency reserves or planned commitments, maintaining adequate liquidity may be more important than seeking higher potential investment returns.
There is no single withdrawal strategy suitable for every NPS subscriber.
Three Things to Review Around Retirement
First, understand how much of your corpus can be withdrawn and how much must be allocated to an annuity under the rules applicable to you.
Second, check whether deferment or phased withdrawal fits your financial requirements. Do not choose it merely because someone assumes that NPS will generate 10% or more every year.
Third, review your nominee and bank-account information before retirement. Correct information can help prevent avoidable problems with withdrawals, pension payments and claim processing.
Market Risk Does Not Disappear at Age 60
Keeping money invested after retirement can support long-term growth, but retirees should remember that investment risk remains.
Equity markets can fall. Bond values can fluctuate. Returns can vary from one year to another.
Someone who needs a particular amount within a short period may therefore require a different asset allocation from someone who does not expect to use the money for another decade.
Retirement planning should balance growth with liquidity and capital stability.
Don't Rush to Close NPS Just Because You Turn 60
The biggest takeaway is that retirement does not necessarily require an immediate exit from every part of your NPS investment.
Depending on the applicable PFRDA rules, eligible subscribers may have options to defer withdrawals or receive the lump-sum portion in a more systematic manner, potentially keeping part of the corpus invested for longer.
This can provide additional time for market-linked compounding, but it does not create a guaranteed 8%, 10% or 12% return.
Before deciding, retirees should compare their monthly income needs, emergency fund, annuity choice, tax position, investment risk and future expenses.
Disclaimer: This article is for informational purposes only and does not constitute investment, tax or retirement-planning advice. NPS returns are market-linked and are not guaranteed. Exit, annuity, deferment and systematic withdrawal rules may be revised by PFRDA. Subscribers should check the latest official NPS/PFRDA regulations and consider professional advice before making retirement-withdrawal decisions.