
New FD Rules From October 1: ₹3 Crore Bulk Deposit Change Explained, Regular Depositors Need Not Worry
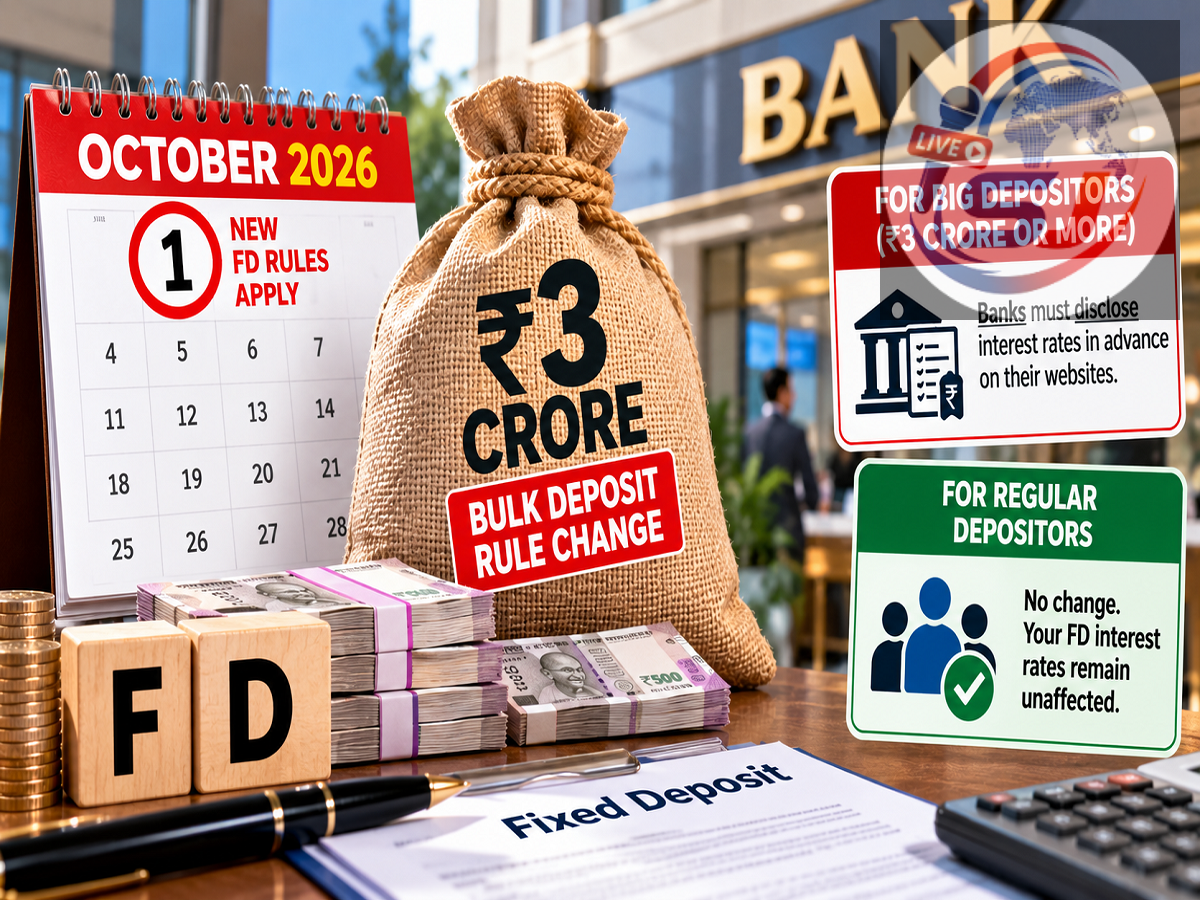
A change related to bank fixed deposits has come into effect from October 1, 2026, but regular FD customers should not assume that their existing interest rates have automatically changed.
The new requirement is primarily relevant to large or bulk deposits of ₹3 crore and above. Under the revised framework described in the source, banks will have to provide greater transparency regarding the interest rates offered on these large deposits.
For customers placing qualifying bulk deposits, the applicable interest rate will need to be disclosed by the bank on its website in advance.
This means the change is mainly about transparency in the pricing of high-value deposits, rather than a blanket revision of interest rates on every fixed deposit account.
What Changes From October 1?
From October 1, banks will have to follow revised disclosure requirements for certain large deposits.
The important threshold for customers to understand is ₹3 crore.
Deposits at or above this level fall into the bulk-deposit category covered by the change described in the source. Banks will be required to make the relevant interest-rate information available on their websites so that eligible depositors can see the rate before placing their money.
The move is intended to make the pricing of large deposits more transparent.
Does the New Rule Apply to Every FD?
No. Regular fixed-deposit customers should not interpret the October 1 change as a new interest-rate rule for all FDs.
If an individual already has a normal fixed deposit below the applicable bulk-deposit threshold, the new disclosure requirement does not mean that the interest rate on that FD will suddenly change from October 1.
Existing FDs generally continue according to the contractual terms applicable when they were booked, unless the deposit's own terms provide otherwise.
The latest change instead focuses on the way banks disclose rates for qualifying large deposits.
Why Is the ₹3 Crore Limit Important?
The distinction between regular and bulk deposits is important because banks may handle the pricing of very large deposits differently from ordinary retail FDs.
Under the framework cited in the source, ₹3 crore is the key threshold for the bulk-deposit rule being discussed.
For example, a customer placing a relatively small FD for personal savings should not automatically assume that the October 1 bulk-deposit requirement applies to that deposit.
On the other hand, someone planning to place ₹3 crore or more should check the bank's published bulk-deposit rate and applicable conditions.
Will Existing FD Interest Rates Change?
The introduction of the new rule does not itself mean that every existing fixed deposit will receive a higher or lower interest rate.
Suppose a customer previously booked an FD at a fixed rate for a specific tenure. The October 1 disclosure change does not, by itself, rewrite the terms of that deposit.
The interest payable on an existing FD will depend on the terms agreed when the deposit was opened.
Similarly, interest rates offered on new retail FDs will continue to depend on the individual bank's prevailing rate card and the chosen tenure.
What Will Banks Have to Do?
For qualifying large deposits, banks will have to provide clearer information about the interest rates they are offering.
Instead of customers having to rely solely on branch-level discussions or individually negotiated information, the relevant rates will need to be disclosed through the bank's website as required under the revised framework described in the source.
This can make it easier for large depositors to understand the rate available before committing a substantial amount of money.
It may also make rate comparison more straightforward for customers considering bulk deposits with different banks.
Regular FD Customers Should Check Their Own Rate Card
Retail FD rates can differ depending on the bank and the tenure selected.
For instance, a bank may offer one interest rate on a one-year deposit and another rate on a three-year or five-year FD. Senior citizens may also receive an additional interest-rate benefit on eligible deposits depending on the bank's policy.
Therefore, customers planning a new FD should check the bank's latest retail deposit rate card instead of assuming that the bulk-deposit change has altered their applicable rate.
What If You Have More Than ₹3 Crore to Deposit?
Customers planning a very large fixed deposit should pay closer attention to the revised framework.
Before placing the deposit, they should check the bank's official website for the applicable bulk-deposit interest rate and read the conditions associated with the deposit.
They should also compare factors such as tenure, premature withdrawal conditions, interest-payment frequency and other applicable terms.
A higher advertised rate alone may not necessarily make one deposit suitable for every customer.
Why Transparency Matters for Large Deposits
Even a small difference in interest rates can have a substantial monetary impact when the principal amount runs into crores of rupees.
For example, a difference of just 0.25 percentage points on ₹3 crore represents:
₹3,00,00,000 × 0.25% = ₹75,000
That illustrates why clear rate disclosure can be particularly important for large depositors.
The actual interest received will, of course, depend on the applicable rate, tenure, compounding method, payout option and tax treatment.
What Should FD Customers Do?
For most ordinary depositors, there is no reason to panic simply because a new FD-related rule has taken effect from October 1.
Customers should first determine whether their deposit actually falls under the relevant bulk-deposit category.
Those holding regular retail FDs can continue to check the interest rate, maturity date and other conditions applicable to their existing deposits.
Anyone opening a new FD should compare the latest rates offered by their bank for the required tenure.
Customers placing ₹3 crore or more should pay particular attention to the published bulk-deposit rates and the bank's applicable terms.
Bottom Line
The October 1 FD change should not be interpreted as an across-the-board change in interest rates for millions of regular fixed-deposit customers.
The key focus is on large deposits of ₹3 crore or more and greater transparency around the rates applicable to them.
Banks will have to disclose the relevant rates on their websites as required under the revised framework, giving large depositors clearer information before they invest.
For regular FD customers, the most important step is simply to check the terms of their existing deposit or the latest retail FD rate offered by their bank before opening a new account.
Disclaimer: This article is for general informational purposes. Fixed-deposit interest rates, eligibility conditions and deposit classifications can vary according to applicable regulations and individual bank policies. Customers should verify the latest terms with their bank before making a deposit.