
New Bank FD Rule From October 1: Bulk Deposit Interest Rates Must Be Disclosed Daily by 10 AM
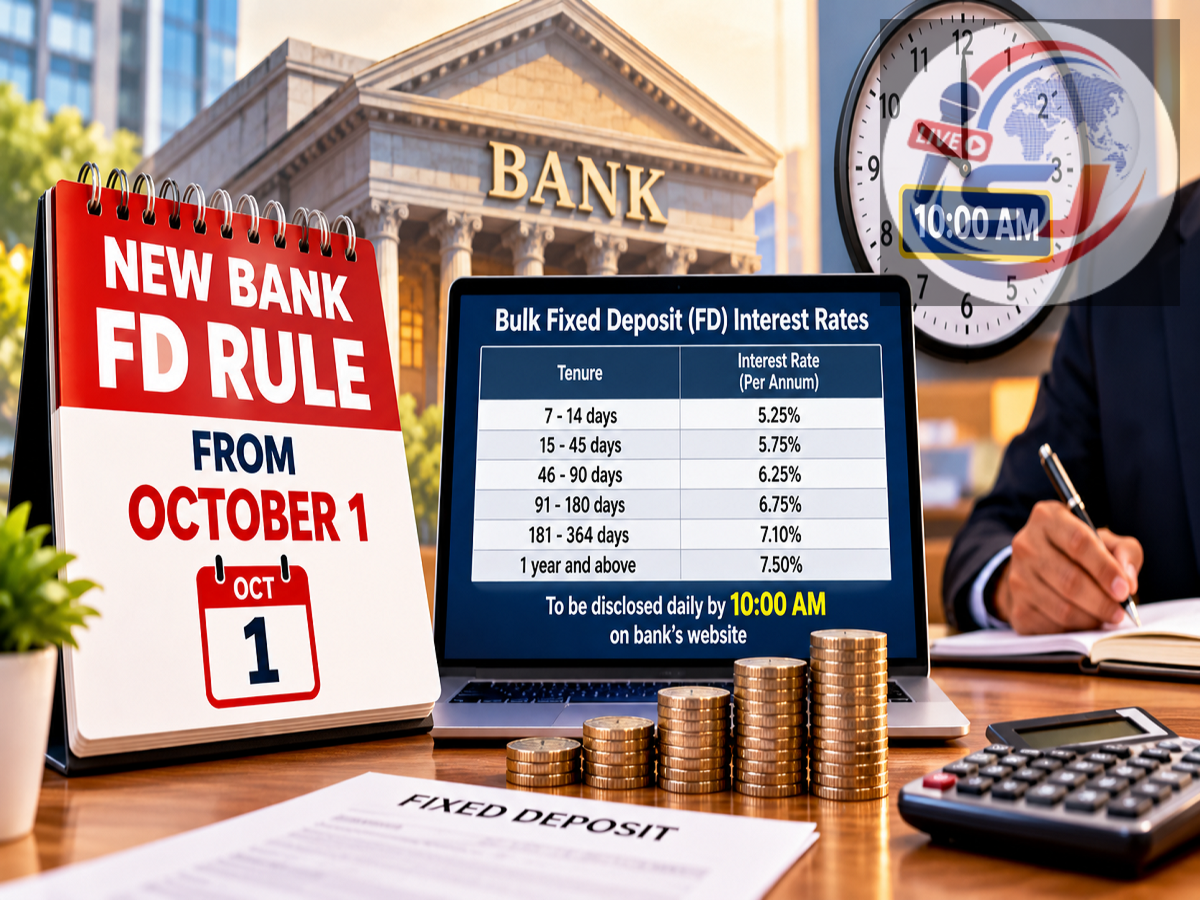
Bulk FD Rule From October 1, 2026: Banks will face a new transparency requirement for bulk fixed deposits from October 1. Under the revised framework cited in the source, banks will have to publish the interest rates offered on bulk term deposits on their websites on every working day.
The rates will need to be made available at a specified time in the morning, with 10 AM becoming the key disclosure time under the new system.
The objective is to make bulk deposit pricing easier to track and compare. However, ordinary retail depositors should understand that this rule relates specifically to bulk deposits and does not mean that the interest rate on every regular FD will change every morning.
What Changes From October 1?
From October 1, 2026, banks covered by the new framework will be required to disclose their applicable bulk fixed-deposit rates on their websites every working day.
According to the details provided, the rates are expected to be published by 10 AM, with a limited operational window extending to around 10:10 AM where applicable.
This creates a more standardised disclosure process for large-value deposits.
Instead of a depositor having to contact multiple banks individually to obtain indicative rates for large deposits, the published information should make prevailing bulk-deposit rates more readily accessible.
What Is a Bulk Fixed Deposit?
A bulk deposit is different from the comparatively smaller fixed deposits commonly opened by individual retail customers.
Banks classify deposits above a specified threshold as bulk deposits under applicable regulatory definitions.
These deposits are often placed by companies, institutions, trusts, government bodies, wealthy individuals and other entities managing large amounts of surplus cash.
Because of the size of these deposits, banks may price them differently from ordinary retail term deposits.
Consequently, the interest rate available on a bulk FD does not necessarily match the rate displayed for a normal household fixed deposit of ₹1 lakh, ₹5 lakh or ₹10 lakh.
Why Is Daily Disclosure Important?
Interest rates offered on large deposits can respond to a bank's liquidity requirements and market conditions.
One bank may offer a different rate from another for a similar tenure, and rates may also vary depending on the deposit amount and maturity period.
Regular website disclosure can therefore improve transparency.
A depositor considering a large term deposit could check the published rates of different banks before deciding where to place the money.
The new disclosure system could also make it easier to identify when a bank has changed its bulk-deposit pricing.
Does This Mean FD Rates Will Change Every Day?
No. This is one of the most important distinctions for depositors.
A requirement to publish rates every working day does not mean banks are required to revise those rates every day.
If a bank's bulk FD rate remains unchanged, it can continue to disclose the applicable rate.
The purpose of the rule is to ensure that current rates are clearly available rather than forcing banks to alter their deposit pricing daily.
Therefore, customers should not interpret the new requirement as meaning that FD returns will automatically move up or down every morning at 10 AM.
Will Your Existing FD Interest Rate Change?
Normally, an existing fixed deposit continues to earn interest according to the rate and contractual conditions applicable when it was booked, unless the particular deposit product provides otherwise.
Suppose a customer has already booked an FD at 7% for a specified tenure. A later change in the bank's rate for newly booked deposits does not ordinarily convert that existing FD to the new rate.
The newly published rate is primarily relevant to deposits being opened or renewed under the applicable terms.
Customers should nevertheless check the conditions of their particular deposit because special products may have different provisions.
Does the New Rule Apply to Regular Retail FDs?
The change highlighted here concerns bulk fixed deposits, so regular retail customers should not assume that the 10 AM daily publication requirement changes the structure of their existing deposits.
Banks already display retail term-deposit rates through their respective channels, and the new bulk-deposit disclosure framework is intended to bring greater visibility to large-value deposit pricing.
Retail customers can still use the development as a reminder to check current FD rates before opening or renewing a deposit.
Why Can Bulk FD Rates Differ From Retail Rates?
It may appear logical that depositing a larger amount should always result in a higher interest rate, but banking does not necessarily work that way.
Bulk deposits can create substantial funding inflows or outflows for a bank. Their pricing may therefore depend on the bank's liquidity position and funding strategy.
As a result, a bulk deposit rate can sometimes be higher than a retail FD rate, while in other situations it may be lower.
Investors should compare actual published rates instead of assuming that a larger deposit automatically earns a better return.
What Should Depositors Compare Besides the Interest Rate?
The headline interest rate is important, but it should not be the only consideration before placing a large amount in a fixed deposit.
Depositors should also examine the tenure, premature-withdrawal conditions, applicable penalties, interest-payment frequency and tax implications.
For large deposits, concentration risk also deserves consideration. Placing a very large amount with one institution simply because it offers a slightly higher rate may not always match the depositor's risk-management needs.
The applicable scope of deposit-insurance protection should also be understood separately rather than assuming that an entire large-value FD is insured.
What Does the 10 AM Deadline Mean for Banks?
Under the framework described in the source, banks will have to ensure that their current bulk-deposit rates are publicly available on their websites each working day around the specified morning deadline.
This can create a clearer reference point for customers, businesses and institutions comparing large deposits.
The important distinction is straightforward:
Banks have to disclose the applicable bulk FD rates daily; they do not necessarily have to change those rates daily.
What Changes for Customers From October 1?
For most ordinary savings-account customers with smaller fixed deposits, there may be no immediate change simply because this disclosure rule takes effect.
The biggest impact will be on customers and organisations dealing with deposits that fall within the applicable bulk-deposit category.
From October 1, 2026, they should be able to check the relevant bank's website around 10 AM on working days to see the applicable bulk FD interest rates.
The move is primarily about transparency and easier comparison of large-value deposit rates rather than changing the interest already locked into every existing fixed deposit.
Note: Bulk-deposit thresholds, eligible institutions, deposit rates and disclosure requirements are governed by applicable banking regulations and individual bank policies. Depositors should check the latest rate and terms with the concerned bank before investing.