
Home Loan Rates October 2026: Interest Starts at 7% at Government Banks, Compare 12 Lenders Before Applying
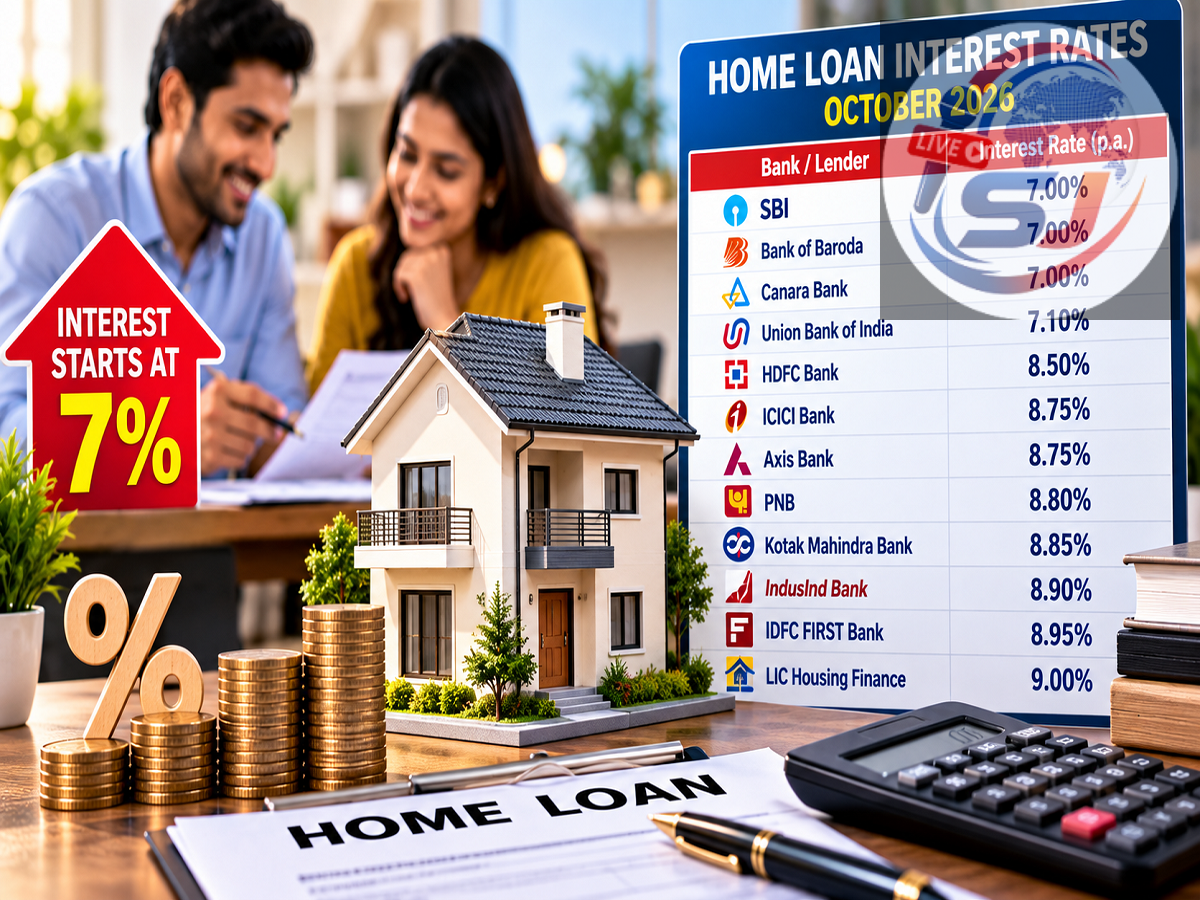
Home Loan Interest Rates October 2026: Planning to purchase your dream home? Before finalising a property or submitting a home loan application, comparing interest rates offered by different banks could help you save a substantial amount over the repayment period.
According to reported October 2026 home loan listings, interest rates at some public sector banks start from 7% per annum. Bank of Maharashtra and Central Bank of India are among the lenders advertising these starting rates, while State Bank of India (SBI) and Bank of India have reported starting rates of 7.25% and 7.10%, respectively.
However, securing a low-interest home loan involves more than comparing advertised rates. Banks consider an applicant's credit score, monthly income, employment stability, loan amount, and repayment history before determining the final interest rate.
Even a small difference in interest rates can significantly affect monthly EMIs and total interest payments, particularly when the repayment period extends to 20 or 30 years.
Here is a detailed overview of the 12 public sector banks covered in the October 2026 comparison, along with important information about home loan eligibility, processing fees, and EMI calculations.
Home Loan Interest Rates October 2026: Compare 12 Government Banks
Several public sector banks are offering home loan products with different interest rate structures and eligibility requirements.
The following table summarises the information available in the reported October 2026 comparison.
| Public Sector Bank |
Reported Starting Interest Rate |
|---|---|
| Bank of Maharashtra |
7.00% |
| Central Bank of India |
7.00% |
| Bank of India |
7.10% |
| Indian Overseas Bank |
7.20% |
| State Bank of India (SBI) |
7.25% |
| Bank of Baroda |
Varies by loan scheme |
| Canara Bank |
Depends on loan amount and category |
| Indian Bank |
Depends on applicable loan offer |
| Punjab & Sind Bank |
Depends on borrower eligibility |
| Punjab National Bank (PNB) |
Varies by loan category |
| UCO Bank |
Depends on applicable loan terms |
| Union Bank of India |
Depends on borrower profile and scheme |
Note: The starting rates shown are based on the supplied October 2026 report and have not been independently verified against current bank rate cards. The source does not provide exact numerical rates for all 12 banks. Borrowers should confirm the latest applicable rates directly with each lender.
Which Government Banks Have Home Loan Rates Starting at 7%?
According to the reported figures, Bank of Maharashtra and Central Bank of India have advertised home loan interest rates starting at 7% per annum.
Bank of India follows with a reported starting rate of 7.10%, while Indian Overseas Bank is listed at 7.20%.
State Bank of India, the country's largest public sector bank, has a reported starting rate of 7.25%.
These rates may attract first-time homebuyers and existing borrowers considering a balance transfer.
However, the lowest advertised interest rate is generally available only to applicants who meet the lender's specific eligibility conditions.
A bank may offer different rates depending on whether the borrower is salaried or self-employed, the loan amount, credit score, property category, and other risk-related factors.
Therefore, borrowers should obtain a personalised loan quotation rather than assuming that the advertised starting rate will automatically apply to their application.
Home Loan EMI Calculator: How Much Will You Pay for a ₹30 Lakh Loan?
Understanding the monthly EMI is one of the most important steps in home loan planning.
Suppose you borrow ₹30 lakh for 20 years.
At an annual interest rate of 7%, the estimated monthly EMI would be approximately ₹23,259.
If the interest rate increases to 8%, the monthly EMI would rise to approximately ₹25,093.
This difference may appear manageable on a monthly basis, but over 20 years it can result in several lakh rupees of additional interest.
Home Loan EMI Calculator
Illustrative
Estimated monthly EMI
₹23,259
Based on a constant annual interest rate and monthly reducing-balance repaymentsLoan amount
₹30,00,000
Annual interest rate
7.00%
Repayment tenure
20 years
Total interest
₹25,82,152
Total repayment
₹55,82,152
Actual EMIs may change for floating-rate loans. Processing fees, insurance, taxes and other charges are excluded.
₹30 Lakh Home Loan: EMI Comparison at Different Interest Rates
Here is an illustrative comparison of monthly EMIs for a ₹30 lakh home loan with a 20-year repayment period.
| Annual Interest Rate |
Approximate Monthly EMI |
|---|---|
| 7.00% |
₹23,259 |
| 7.10% |
₹23,441 |
| 7.20% |
₹23,622 |
| 7.25% |
₹23,713 |
| 7.50% |
₹24,168 |
| 8.00% |
₹25,093 |
| 8.50% |
₹26,035 |
| 9.00% |
₹26,992 |
These figures demonstrate why borrowers should compare interest rates carefully before choosing a home loan.
A lower rate can reduce the monthly repayment burden and potentially save a substantial amount over the loan's lifetime.
Why Is Your Credit Score Important for Home Loan Approval?
Banks use credit scores and repayment histories to evaluate the financial reliability of loan applicants.
A borrower with a strong credit profile may have better chances of qualifying for competitive interest rates.
Applicants with previous loan defaults, repeated payment delays, or significant outstanding debt may face stricter eligibility conditions.
Banks may also consider the applicant's income stability, employment type, age, and existing monthly financial commitments.
Maintaining a healthy credit profile before applying for a home loan can therefore be beneficial.
However, no particular credit score guarantees approval or the lowest advertised rate.
Home Loan Processing Fees: What Other Charges Should You Check?
The interest rate is only one component of the total home loan cost.
Banks may charge processing fees, property valuation expenses, legal verification fees, and other applicable charges.
Property purchases may also involve stamp duty, registration fees, and other transaction-related expenses.
Some banks offer promotional processing fee waivers or discounts during specific periods, subject to their terms.
Before accepting a loan offer, borrowers should request a complete breakdown of all charges.
The lender's Key Facts Statement can help explain the applicable annual percentage rate, repayment conditions, and other important borrowing costs.
Comparing the overall cost is more useful than focusing exclusively on the headline interest rate.
Fixed vs Floating Home Loan Interest Rates: Which Should You Choose?
Home loans may be available with fixed, floating, or hybrid interest rate structures.
A fixed-rate loan generally keeps the contracted interest rate unchanged for the specified fixed-rate period, subject to the agreement.
A floating-rate loan can change when the applicable benchmark or lending rate is revised.
For example, if the benchmark linked to a floating-rate loan rises, the borrower's interest burden may increase.
Conversely, a reduction in the applicable benchmark may lower the borrowing cost, depending on the loan's reset terms.
Borrowers should carefully examine how frequently their interest rate can change and whether adjustments affect the EMI, loan tenure, or both.
How to Reduce Your Home Loan Interest Burden
There are several ways borrowers can manage long-term home loan expenses.
Maintaining a strong credit score and comparing offers from multiple banks can improve the chances of securing favourable loan terms.
Choosing a suitable repayment tenure is equally important.
A shorter tenure generally results in higher monthly EMIs but lower total interest payments.
Borrowers with surplus savings may also consider partial prepayments, subject to the applicable loan terms.
Making additional principal repayments can reduce the outstanding loan balance and potentially lower future interest expenses.
However, borrowers should maintain sufficient emergency savings before committing large amounts to loan prepayments.
Should You Transfer Your Existing Home Loan to Another Bank?
Existing home loan borrowers may consider transferring their outstanding balance to another lender if the new bank offers more favourable terms.
A balance transfer may reduce interest expenses, particularly when the remaining loan amount is substantial and several years of repayment are still left.
However, borrowers should account for processing charges, documentation expenses, and other transfer-related costs.
The potential savings should exceed the expenses involved in switching lenders.
It is also worth asking the existing bank whether it can offer a lower interest rate before proceeding with a transfer.
Important Things to Check Before Applying for a Home Loan
Buying a home is a major financial commitment, and the repayment period may extend over several decades.
Before applying, borrowers should calculate the required down payment and estimate their monthly EMI.
They should also consider property registration expenses, maintenance costs, insurance, and other financial responsibilities associated with homeownership.
It is important to ensure that the EMI remains affordable after accounting for household expenses and existing loan repayments.
Applicants should also verify the property's legal documentation and the lender's loan approval conditions.
Comparing multiple offers can help borrowers understand the differences in interest rates, repayment flexibility, and additional charges.
Final Takeaway
The reported October 2026 home loan comparison indicates that starting interest rates at some public sector banks are as low as 7% annually.
Bank of Maharashtra and Central Bank of India are listed with starting rates of 7%, followed by Bank of India at 7.10%, Indian Overseas Bank at 7.20%, and SBI at 7.25%.
For a ₹30 lakh home loan over 20 years, an interest rate of 7% results in an estimated monthly EMI of ₹23,259, compared with approximately ₹25,093 at 8%.
Before choosing a home loan, compare the actual interest rate offered to you, processing fees, repayment conditions, and total interest cost across multiple banks.
A carefully selected home loan can make homeownership more manageable while helping borrowers avoid unnecessary financial pressure over the long term.
Disclaimer: The bank interest rates mentioned are based on the supplied October 2026 report and have not been independently verified. Interest rates, fees, and eligibility criteria may change. EMI calculations are illustrative and do not constitute a loan offer or financial advice.