EPFO Wage Limit Rises to ₹25,000: What Changes for Employees Earning ₹15,000 or More?
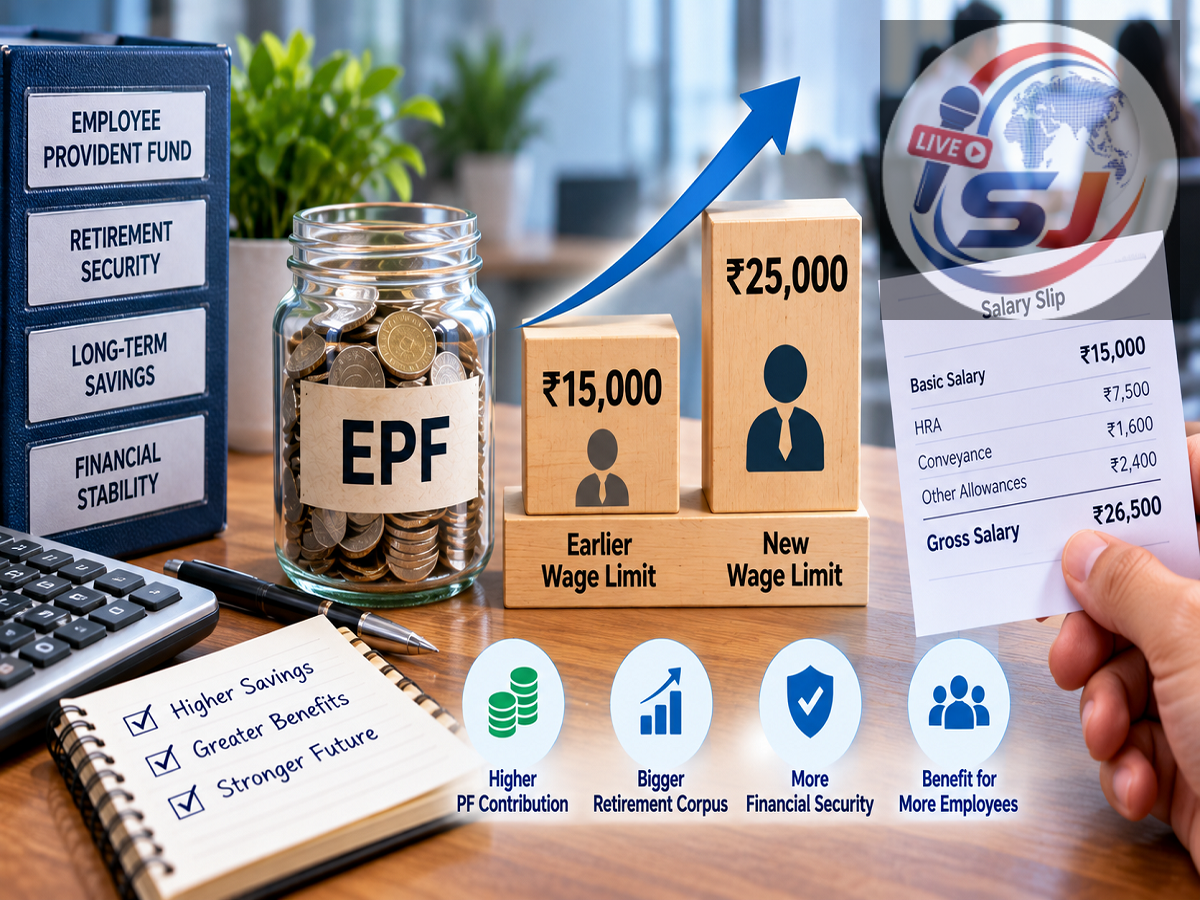
A major change in the Employees’ Provident Fund (EPF) framework has put the spotlight on the monthly wage ceiling used for mandatory social-security coverage. The government has decided to increase the wage ceiling under EPFO from ₹15,000 to ₹25,000 per month, expanding the scope of mandatory coverage to a larger group of salaried employees.
For workers whose Basic salary plus Dearness Allowance (DA) is ₹15,000 or below, the immediate question is whether the higher ceiling will automatically increase their monthly PF deduction. Employees earning between ₹15,000 and ₹25,000, meanwhile, may want to know whether they will now come under mandatory EPF coverage and how that could affect take-home pay.
The impact is not identical for everyone. It depends on an employee’s wages, existing EPF membership and salary structure.
What Does the New ₹25,000 EPFO Wage Ceiling Mean?
Until this change, ₹15,000 per month was the wage ceiling used for mandatory EPF coverage under the applicable rules. The new decision raises this threshold to ₹25,000.
In simple terms, the change expands the salary range within which eligible workers can come under compulsory EPFO coverage.
The earlier ₹15,000 ceiling had been in place since 2014. The increase therefore represents a significant expansion of the statutory social-security threshold after around 12 years.
However, employees should not confuse the wage ceiling with gross salary, CTC or take-home pay. EPF rules use the applicable wage components, commonly including Basic wages and DA, according to the statutory framework.
What Happens If Your Basic + DA Is ₹15,000?
Employees whose applicable wages are ₹15,000 or less were already within the mandatory EPF framework.
For this group, raising the wage ceiling from ₹15,000 to ₹25,000 does not by itself create a new coverage requirement because they were already covered under the earlier threshold.
Under the standard structure, employees generally contribute 12% of applicable EPF wages, with the employer also making the prescribed contribution.
Therefore, an employee whose Basic + DA remains ₹15,000 should not assume that their PF deduction will suddenly be calculated on ₹25,000 merely because the statutory ceiling has been increased.
At 12%, an employee contribution calculated on ₹15,000 works out to ₹1,800 per month. If the underlying PF wages remain ₹15,000, simply changing the maximum coverage threshold does not turn the employee’s wages into ₹25,000.
Why Employees Earning ₹15,000-₹25,000 Are More Affected
The more significant impact is on employees whose applicable monthly wages fall above ₹15,000 but up to ₹25,000.
Under the earlier ceiling, some new employees in this salary range could fall outside mandatory EPF coverage, depending on their membership status and applicable rules.
Once the higher ceiling applies, a wider group of employees in this bracket can come under compulsory EPFO coverage.
This could strengthen long-term social-security protection by enabling eligible employees to accumulate provident-fund savings and receive benefits under the associated EPFO schemes, subject to their respective rules.
Could PF Deduction Increase for Newly Covered Employees?
For employees entering mandatory EPF coverage for the first time, there can be a noticeable change in the monthly salary structure.
EPF requires an employee contribution. Therefore, if a worker who previously did not contribute to EPF becomes mandatorily covered under the revised threshold, a PF deduction can begin appearing in the monthly salary slip.
For example, an employee with applicable PF wages of ₹20,000 could see an employee contribution based on the contribution rules that apply after implementation.
This is why it would be misleading to say that the wage-ceiling increase can never affect take-home salary.
Will Take-Home Salary Fall?
For employees already contributing to EPF on the same applicable wages, there may be little or no immediate difference solely because the coverage ceiling has increased.
The situation can be different for someone who becomes an EPFO member because of the expanded mandatory coverage.
Since part of the employee’s salary is contributed toward EPF, the amount received as monthly cash salary can be lower than it would be without that deduction. The precise impact will depend on the employee’s salary structure and how the employer implements the revised requirements.
At the same time, that deduction is not simply an expense. The employee contribution is credited toward the worker’s provident-fund savings, where it can accumulate with applicable interest.
What About the Employer's 12% Contribution?
Employers generally make a prescribed contribution alongside the employee contribution. However, the employer’s entire contribution should not be described as going directly into the employee’s EPF balance.
The employer-side contribution is allocated between EPF and the Employees’ Pension Scheme (EPS) according to the applicable rules and eligibility conditions.
This distinction becomes particularly important when discussing the higher wage ceiling because EPF coverage and EPS contribution calculations are related but have their own statutory provisions.
Employees should therefore check the implementation rules rather than assuming that every 12% employer contribution will be deposited entirely into their provident-fund account.
Why Raising the Wage Ceiling Matters
The previous ₹15,000 ceiling had remained unchanged for years, while salaries and living costs continued to increase.
As wages rise, more workers can move beyond an old statutory threshold. Increasing the ceiling to ₹25,000 can bring more employees within the formal retirement and social-security framework.
For newly covered workers, regular PF contributions can help build a long-term retirement corpus. Eligible employees may also receive pension-related and insurance benefits under EPFO-administered schemes, subject to their respective conditions.
The trade-off for some newly covered employees is that mandatory contributions can reduce immediately available take-home salary.
₹15,000 Salary Employees Should Not Panic About a Sudden Deduction Jump
The most important distinction is between raising the coverage ceiling and raising an employee’s actual PF wages.
If an employee’s Basic + DA is ₹15,000, increasing the maximum mandatory coverage ceiling to ₹25,000 does not automatically mean PF will now be deducted as though that employee earns ₹25,000.
The larger impact is expected among workers earning more than the previous ₹15,000 threshold but falling within the new ₹25,000 limit.
Employees who are brought into mandatory EPFO coverage for the first time may see a change in their salary slips and take-home pay because employee PF contributions will have to be accounted for.
Existing EPFO members, meanwhile, should check their Basic + DA, current PF contribution and employer payroll structure to understand whether anything actually changes for them.
Ultimately, the higher ₹25,000 ceiling is primarily an expansion of EPFO coverage, rather than an automatic increase in PF deductions for every existing employee earning ₹15,000 a month.