Breaking Your FD Before Maturity? Check These 5 Rules to Avoid Losing Interest and Paying a Penalty
Fixed deposits are widely used by people who want predictable returns without exposing their savings to stock-market fluctuations. You invest a lump sum for a selected tenure, and the bank pays interest according to the applicable FD rate.
However, financial emergencies do not always wait for an FD to mature. Medical expenses, education costs, home repairs or another urgent requirement may force a depositor to withdraw the money earlier than planned.
This is known as premature FD withdrawal or premature closure.
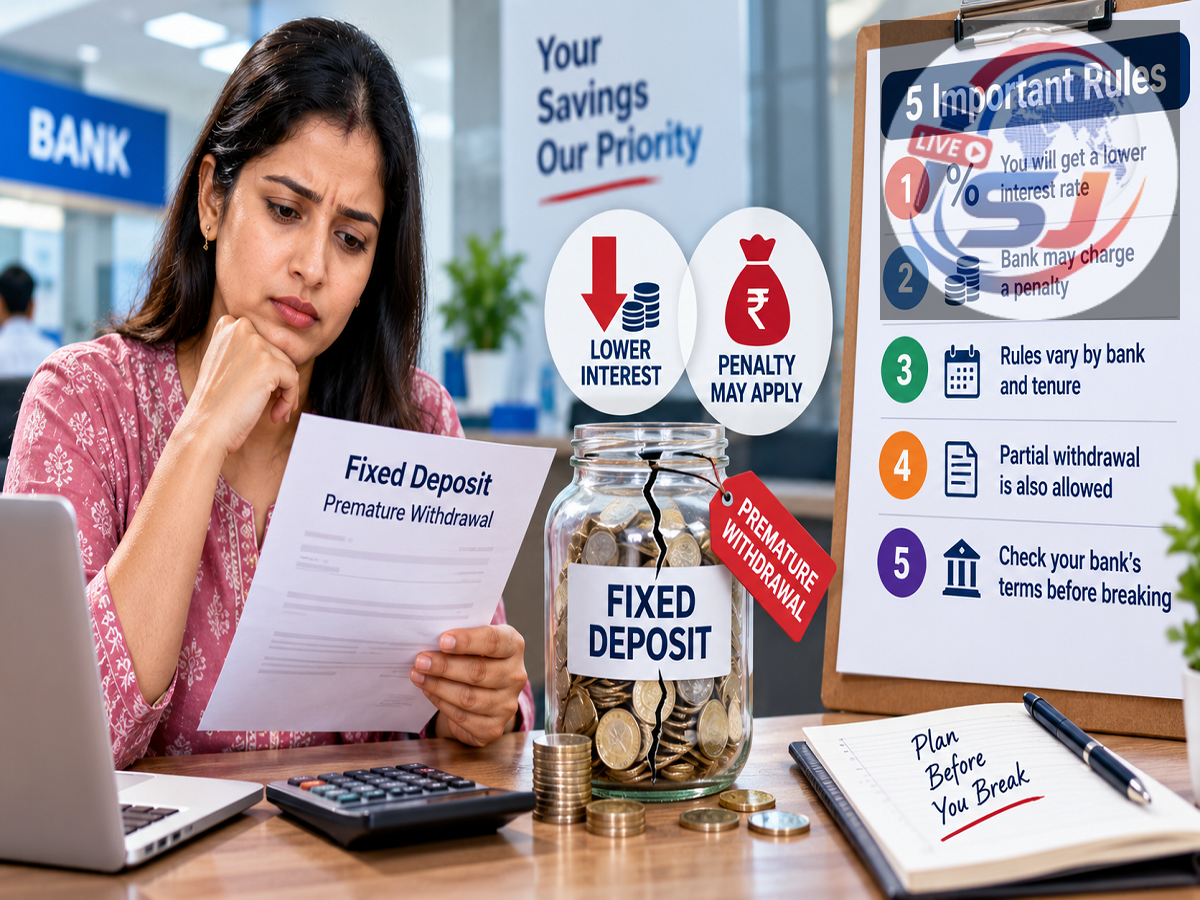
Although many regular bank FDs can be closed before maturity, doing so can reduce your expected return. The depositor may receive a lower applicable interest rate, and the bank may also impose a premature-withdrawal penalty.
Before breaking an FD in 2026, understanding these five important rules can help you estimate the actual cost.
1. Premature Closure Can Reduce Your Effective Interest Rate
The first thing to understand is that the interest rate mentioned when you originally booked the FD may not be the rate you finally receive if you close it early.
Suppose you invested money in a five-year FD carrying an interest rate of 7.5% per annum. If you withdraw the deposit after only two years, the bank will generally not calculate your return using the five-year rate merely because that was the original tenure.
Instead, the interest may be recalculated according to the bank's premature-closure terms and the rate applicable for the period for which the money actually remained deposited.
This can significantly reduce the expected return.
2. Banks May Also Apply a Premature Withdrawal Penalty
In addition to recalculating the interest, banks may impose a penalty when an FD is closed before maturity.
Depending on the bank, deposit amount, customer category and FD product, the penalty may commonly be expressed as a reduction in the applicable interest rate.
For example, if the applicable rate for the period the deposit actually remained with the bank is 7%, and the bank imposes a 1 percentage-point premature-withdrawal penalty, the effective interest calculation could be based on 6%, subject to that bank's exact terms.
Therefore, it is important to understand that the penalty mechanism is not necessarily a straightforward deduction of 1% from your principal amount.
Banks can have different premature-closure policies, so customers should check the specific terms applicable to their deposit.
3. Your Original FD Rate May Not Decide the Final Return
This is where many depositors become confused.
Consider an investor who places ₹5 lakh in an FD for five years at 7.5%. After two years, the investor needs the money and decides to close the deposit.
The bank will check the rate applicable under its rules for the period the FD actually remained invested. The premature-closure penalty, if applicable, is then considered according to the bank's policy.
As a result, the investor may earn substantially less than originally expected.
The exact calculation can differ among banks. Therefore, before confirming premature closure through mobile banking or internet banking, check the amount the bank says will actually be credited.
4. Five-Year Tax-Saving FDs Have Different Withdrawal Rules
A regular FD should not be confused with a five-year tax-saving fixed deposit.
Tax-saving FDs eligible for deduction under Section 80C, subject to the applicable income-tax framework, come with a mandatory five-year lock-in.
These deposits generally cannot be prematurely withdrawn during the lock-in period.
This restriction is one of the major differences between an ordinary fixed deposit and a tax-saving FD.
Investors should therefore think carefully about liquidity before putting a large portion of their emergency savings into a tax-saving deposit.
Also remember that the Section 80C benefit is relevant only where the taxpayer is eligible to claim it under the tax regime and provisions applicable to them.
5. Consider a Loan or Overdraft Against FD Before Breaking It
If you need money temporarily, closing the FD may not always be the most economical option.
Many banks provide a loan or overdraft against fixed deposits. The FD continues to earn interest while the customer borrows against its value.
Depending on the bank and product, a substantial percentage of the FD value may be available as a loan or overdraft. Some banks can offer funding of around 90% or more of the deposit value, although the exact limit varies.
The interest charged on such borrowing is usually linked to the FD rate with an additional spread determined by the bank.
For example, if you need ₹1 lakh temporarily but have an FD of ₹5 lakh, borrowing against the deposit may be worth comparing with the cost of prematurely closing the entire ₹5 lakh FD.
Loan Against FD vs Premature Withdrawal: Which Is Better?
There is no single answer for every investor.
If you urgently need almost the entire FD amount and do not expect to repay borrowed money soon, premature closure may be more practical.
On the other hand, if the requirement is temporary and significantly smaller than the FD amount, a loan or overdraft against the deposit could help preserve the original investment.
Compare the interest cost of the loan with the loss you would suffer from the lower FD rate and premature-withdrawal penalty.
The cheaper option will depend on the deposit terms, remaining tenure and amount required.
Another Strategy: Create Multiple Smaller FDs
Investors can also plan ahead to reduce the impact of a future emergency.
Instead of investing ₹10 lakh in one FD, for example, you could consider splitting the amount into several smaller deposits.
If you later need only ₹2 lakh, you may be able to close one smaller FD rather than breaking the entire ₹10 lakh deposit.
This strategy is sometimes referred to as FD laddering or splitting deposits, depending on how the deposits and maturity dates are structured.
It can provide greater liquidity while allowing the remaining deposits to continue earning interest.
Check Whether Your FD Has Special Conditions
Not every fixed deposit follows exactly the same premature-withdrawal rules.
Banks can offer regular FDs, non-callable deposits, senior-citizen deposits, tax-saving deposits and other variants. Certain products may restrict premature withdrawal or follow different penalty conditions.
Even within the same bank, rules can vary depending on the deposit amount and tenure.
That is why investors should not assume that a penalty charged on someone else's FD will automatically apply to theirs.
Check the deposit receipt, bank website, mobile banking application or official terms and conditions for your particular FD.
Calculate the Cost Before Clicking 'Close FD'
Premature FD withdrawal can provide quick access to money, but convenience may come at the cost of lower returns.
Before closing the deposit, check the interest rate applicable for the actual period completed, the premature-closure penalty, the final amount payable and whether a loan or overdraft against the FD would cost less.
Tax-saving FDs require even greater attention because their five-year lock-in generally prevents premature withdrawal.
If liquidity is likely to be important, splitting your savings across multiple deposits and keeping a separate emergency fund can reduce the need to break a large FD unexpectedly.
A few minutes spent checking these rules before withdrawing can prevent an unpleasant surprise when the final maturity or closure amount reaches your bank account.