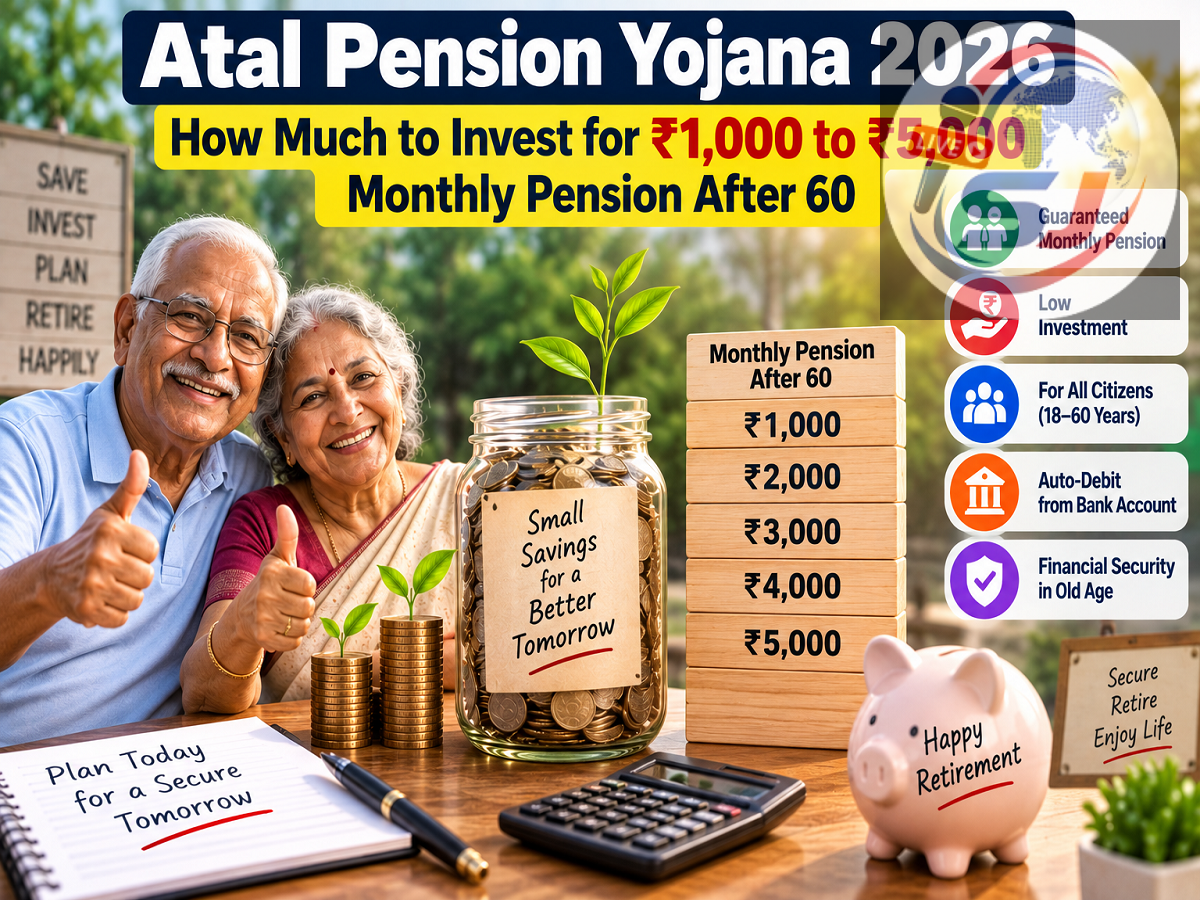
Atal Pension Yojana 2026: How Much to Invest for ₹1,000 to ₹5,000 Monthly Pension After 60
Planning for retirement is particularly important for people who may not receive a regular employer-backed pension after leaving work. The Atal Pension Yojana (APY) is a government-backed pension scheme designed primarily to provide retirement income security, especially to workers in the unorganised sector.
Under APY, eligible subscribers make regular contributions until the age of 60. The contribution depends on two important factors—the subscriber's age when joining and the pension amount selected.
After reaching 60, the subscriber can receive a guaranteed minimum pension of ₹1,000, ₹2,000, ₹3,000, ₹4,000 or ₹5,000 per month, depending on the pension option chosen and the required contributions made under the scheme.
One of the biggest advantages of joining at a younger age is that the required periodic contribution is lower because the subscriber has more years available to contribute.
How Much Monthly Pension Can You Get Under APY?
Atal Pension Yojana provides five guaranteed minimum pension options.
| Pension Option | Guaranteed Minimum Monthly Pension After 60 |
|---|---|
| Option 1 | ₹1,000 |
| Option 2 | ₹2,000 |
| Option 3 | ₹3,000 |
| Option 4 | ₹4,000 |
| Option 5 | ₹5,000 |
The selected pension becomes payable after the subscriber reaches the age of 60, subject to the applicable APY rules and required contributions.
The contribution is not the same for everyone. A person joining at 18 generally contributes much less than someone entering the scheme closer to the maximum joining age.
Want ₹5,000 Pension? Starting at 18 Requires a Lower Contribution
The age at which you join APY has a major impact on the contribution.
For example, according to the APY contribution structure, a person entering at 18 years of age and selecting the ₹5,000 monthly pension option contributes ₹210 per month.
This is possible because the individual has approximately 42 years to contribute before turning 60.
Someone starting much later would need to contribute substantially more each month for the same ₹5,000 guaranteed minimum pension because the contribution period would be shorter.
This is why joining early can significantly reduce the amount that needs to be set aside periodically.
Who Is Eligible to Join Atal Pension Yojana?
The basic entry age for APY is 18 to 40 years.
The applicant needs an eligible savings bank account or post-office savings account for contributions to be collected through auto-debit.
However, there is another important eligibility rule that prospective subscribers should know.
From October 1, 2022, a citizen who is or has been an income-tax payer is not eligible to open a new Atal Pension Yojana account under the applicable rules.
Therefore, APY should not be described as being available without restriction to every citizen between 18 and 40.
People considering enrollment should check their eligibility before submitting an application.
What Happens After the Subscriber Turns 60?
After reaching 60 years of age, the subscriber becomes eligible for the guaranteed minimum pension selected under the scheme, subject to APY conditions.
The available pension slabs range from ₹1,000 to ₹5,000 per month.
APY also contains benefits for the subscriber's spouse and nominee.
After the subscriber's death, the spouse can receive the same pension amount under the applicable scheme provisions.
After the death of both the subscriber and spouse, the accumulated pension wealth corresponding to the selected pension level is returned to the nominee as prescribed under APY.
This structure is intended to provide financial support not only to the subscriber but also to the family.
How Are APY Contributions Collected?
APY contributions are generally collected automatically from the subscriber's linked savings account.
Subscribers can contribute at the prescribed frequency, including monthly, quarterly or half-yearly, according to the available scheme provisions.
Once the contribution arrangement is established, the required amount is automatically debited from the registered account.
The subscriber should therefore ensure that sufficient funds are available when the contribution becomes due.
Failure to maintain enough balance can lead to overdue contributions and charges or other consequences under the applicable rules.
Can You Open an APY Account Online?
Digital enrollment facilities have made joining APY easier for eligible applicants.
Depending on the bank and available services, customers may be able to enrol through internet banking, mobile banking or supported digital APY onboarding facilities.
The exact procedure can vary between banks.
Typically, an eligible applicant needs to provide the required personal details, select the desired pension amount, provide nominee and spouse information where applicable, and authorise auto-debit of contributions.
After successful registration, a Permanent Retirement Account Number (PRAN) is generated for the subscriber.
Claims that every applicant can complete the entire process in exactly “five minutes” should be treated as promotional estimates rather than a guaranteed processing time. Actual completion time depends on the bank, verification and the applicant's information.
Why Starting Early Makes a Big Difference
APY's contribution structure rewards early enrollment through lower required contributions.
Someone joining at 18 has decades to build the corpus needed to support the selected pension. A person entering at 35 or 40 has far fewer contribution years and therefore needs to deposit more periodically.
For younger eligible workers, this means retirement planning can begin with a comparatively small regular contribution.
The key is consistency. Since contributions continue until 60, subscribers should select a pension level and contribution amount that they can reasonably maintain over the long term.
Does APY Offer Tax Benefits?
Contributions to Atal Pension Yojana can qualify for tax treatment under the applicable provisions governing contributions to the National Pension System framework.
However, taxpayers need to be particularly careful with this point because income-tax payers are no longer eligible to newly join APY from October 1, 2022.
Tax treatment can also depend on the subscriber's circumstances and the tax regime selected.
Therefore, prospective subscribers should not join APY solely on the assumption that they will automatically receive an additional tax deduction. Existing subscribers should check the latest income-tax provisions applicable to their situation.
What Should You Check Before Joining?
Before enrolling, first confirm that you satisfy the APY eligibility conditions, particularly the age and income-tax-payer restrictions.
Next, decide how much guaranteed minimum monthly pension you want after turning 60. The selected pension level and your entry age determine how much you need to contribute.
You should also keep sufficient balance in the linked account for automatic deductions and make sure nominee and spouse details are accurate.
For someone eligible to join at a young age, APY can provide a structured way of building a basic pension for retirement. An 18-year-old choosing the highest available guaranteed minimum pension of ₹5,000 per month, for example, has a prescribed contribution of ₹210 per month.
However, the maximum ₹5,000 monthly pension should be viewed as a basic retirement-income layer rather than necessarily being sufficient for all expenses several decades in the future, particularly after accounting for inflation.
Disclaimer: Atal Pension Yojana eligibility, contributions, pension benefits, exit conditions and tax treatment are governed by applicable government and PFRDA rules. Applicants should verify the latest official APY terms before enrolling.